Stop foreclosure help in Bustleton, Philadelphia with Andre Richardson, Realtor — the go-to agent for foreclosure help in Bustleton
Stop Foreclosure

Foreclosure Help
in Bustleton

You have more options than you think.

Bustleton is a convenient, family-friendly corner of the Northeast, where brick rowhomes and twins line blocks close to shopping, schools, and major corridors. Homeowners here value the combination of affordability and accessibility, and the equity built through steady ownership is real. I'm Andre Richardson, and for 26 years I've been involved with Philadelphia real estate. Facing foreclosure doesn't mean your story is over. It means it's time to look at your options, and the earlier you do, the more choices you have.

26 Years
Real Estate Experience
5.0
Rating from 27 Reviews
AI
Powered Marketing
PA & NJ
Licensed
01
Why It Matters

Why Acting Early Matters
in Bustleton

Bustleton is a family-friendly corner of the Northeast where brick rowhomes and twins sit along busy, convenient corridors close to shopping and schools. For most Bustleton homeowners, the house is the largest asset they own, and the equity built through steady ownership is real and worth protecting. When a mortgage becomes hard to keep up with, that equity is exactly what makes acting early matter.

  • The earlier you act, the more options you have: a repayment plan, forbearance, a loan modification, a short sale, or a sale at full market value
  • Bustleton's convenience and family-friendly blocks keep a steady pool of buyers, which works in your favor when you need to sell on a timeline
  • Time protects equity: every month spent waiting narrows the gap between what you owe and what your home is worth
  • Solutions like a loan modification are far easier to secure before the process moves deep into the courts

Foreclosure in Pennsylvania is a judicial process, which means it moves in stages and there is a path forward at every stage. The mistake homeowners make is waiting to find it. The homeowners who call early keep control of the outcome, and in Bustleton, where steady ownership built the equity, early action is how that equity gets protected.


02
Your Options

Options Beyond Foreclosure,
with Someone on Your Side

You have more options than you think. Each path below is a real, workable route, and every one of them goes better with Andre Richardson leading the way. He listens to your situation first, then builds the plan around your lender and your timeline.

Working with your lender

Before anything else, there may be room to work directly with your mortgage servicer: a repayment plan to catch up on missed payments, a forbearance that pauses payments for a set period, or a reinstatement agreement. Andre reviews your specific situation, and if speaking with your lender is the best route, he guides you to coordinate with your lender.

A loan modification

A loan modification rewrites the terms of your mortgage so the payment fits your current income, through a lower rate, a longer term, or added arrears. Modifications are far more attainable early in the process, and Andre will point you to talk with your lender.

A professionally guided short sale

If you owe more than the home can sell for, a short sale lets you sell with the lender's approval and walk away from the threat of foreclosure. Andre manages the entire negotiation for you, from the loss mitigation department to the paperwork, and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

Selling before foreclosure

If your Bustleton home holds equity, selling on the open market before the sheriff sale is often the strongest path. You capture the value your home has built, pay off the mortgage, protect your credit, and close the chapter on your terms, with Andre's aggressive AI-infused marketing working towards getting your home sold.

These paths are explained step by step in the full foreclosure and short sale guidance for Philadelphia, covering timelines, credit impacts, and lender negotiations. If the mortgage weighs more than the home can carry, the short sale guidance in Bustleton page walks through selling for less than you owe with the lender's approval. And if your home has already been through a listing that did not sell, the expired listing help in Bustleton page shows how a relaunch gets it sold. You do not have to choose a path alone.


03
The Agent

Why Sellers Trust Andre

By the time Bustleton homeowners facing foreclosure find me, many have been carrying the weight of the situation alone for months, and some have watched a previous listing fail. I bring 26 years of Philadelphia and South Jersey experience, active PA and New Jersey licenses, and a targeted marketing plan that gets homes sold. Every conversation is confidential, and there is no judgment, only solutions.

“Andre was very professional and knowledgeable, a definite credit to the profession. I would not hesitate to refer him to any of my friends or family for his real estate services. Andre did not hesitate to go above and beyond to make things happen. Job well done for me thank you Andre!”

— Stella Thompson, 5-star review

See how the sell my house process works or read the client reviews from sellers who started right where you are.


04
Answers

Questions Bustleton Homeowners
Facing Foreclosure Ask

Can I sell my Bustleton home after receiving a foreclosure notice?

Yes. You can sell at any point before the sheriff sale, and in Bustleton, where brick rowhomes and twins hold steady value, selling before foreclosure is often the strongest path. A sale at or near market value lets you pay off the mortgage, keep what equity remains, and protect your credit. The key is starting now, because the timeline moves faster than most homeowners expect.

How long do I have before a sheriff sale in Pennsylvania?

The foreclosure process in Pennsylvania typically runs six to twelve months from the first missed payment to the sheriff sale, and federal law requires a 120-day waiting period before a lender can even begin formal proceedings. Philadelphia's Mortgage Foreclosure Diversion Program, which requires a conciliation conference, can extend that window. In Bustleton, using that window to list early is what lets you capture full value.

I owe less than my Bustleton home is worth. Can I still sell before foreclosure?

Yes, and that is the strongest position to be in. Bustleton's brick rowhomes and twins hold steady value because the neighborhood stays in demand with families who want convenience and affordability. If you can sell for enough to satisfy the mortgage, a traditional pre-foreclosure sale preserves that equity and keeps the credit impact minimal. The earlier you list, the more time you have to capture the full value Bustleton buyers are willing to pay.

Will a short sale protect me from the lender coming after the difference?

Pennsylvania is a recourse state, which means a deficiency judgment is possible after a foreclosure or a short sale unless it is waived. That is why the short sale agreement should include a deficiency waiver, a written provision that the lender will not pursue you for the remaining balance. Andre negotiates for that protection in every short sale he manages. A short sale also impacts credit far less than a completed foreclosure, and you can qualify for a new mortgage years sooner.

What happens if I do nothing?

If nothing changes, the process continues through the courts to a sheriff sale, where the property is sold at auction either to a private buyer or to the lender. You lose the equity in the home, your credit takes its hardest hit, and a deficiency judgment remains possible in Pennsylvania. That outcome is almost always avoidable, and the homeowners who call early keep the most control over how their story ends.

05
From the Blog

Bustleton Foreclosure
Advice

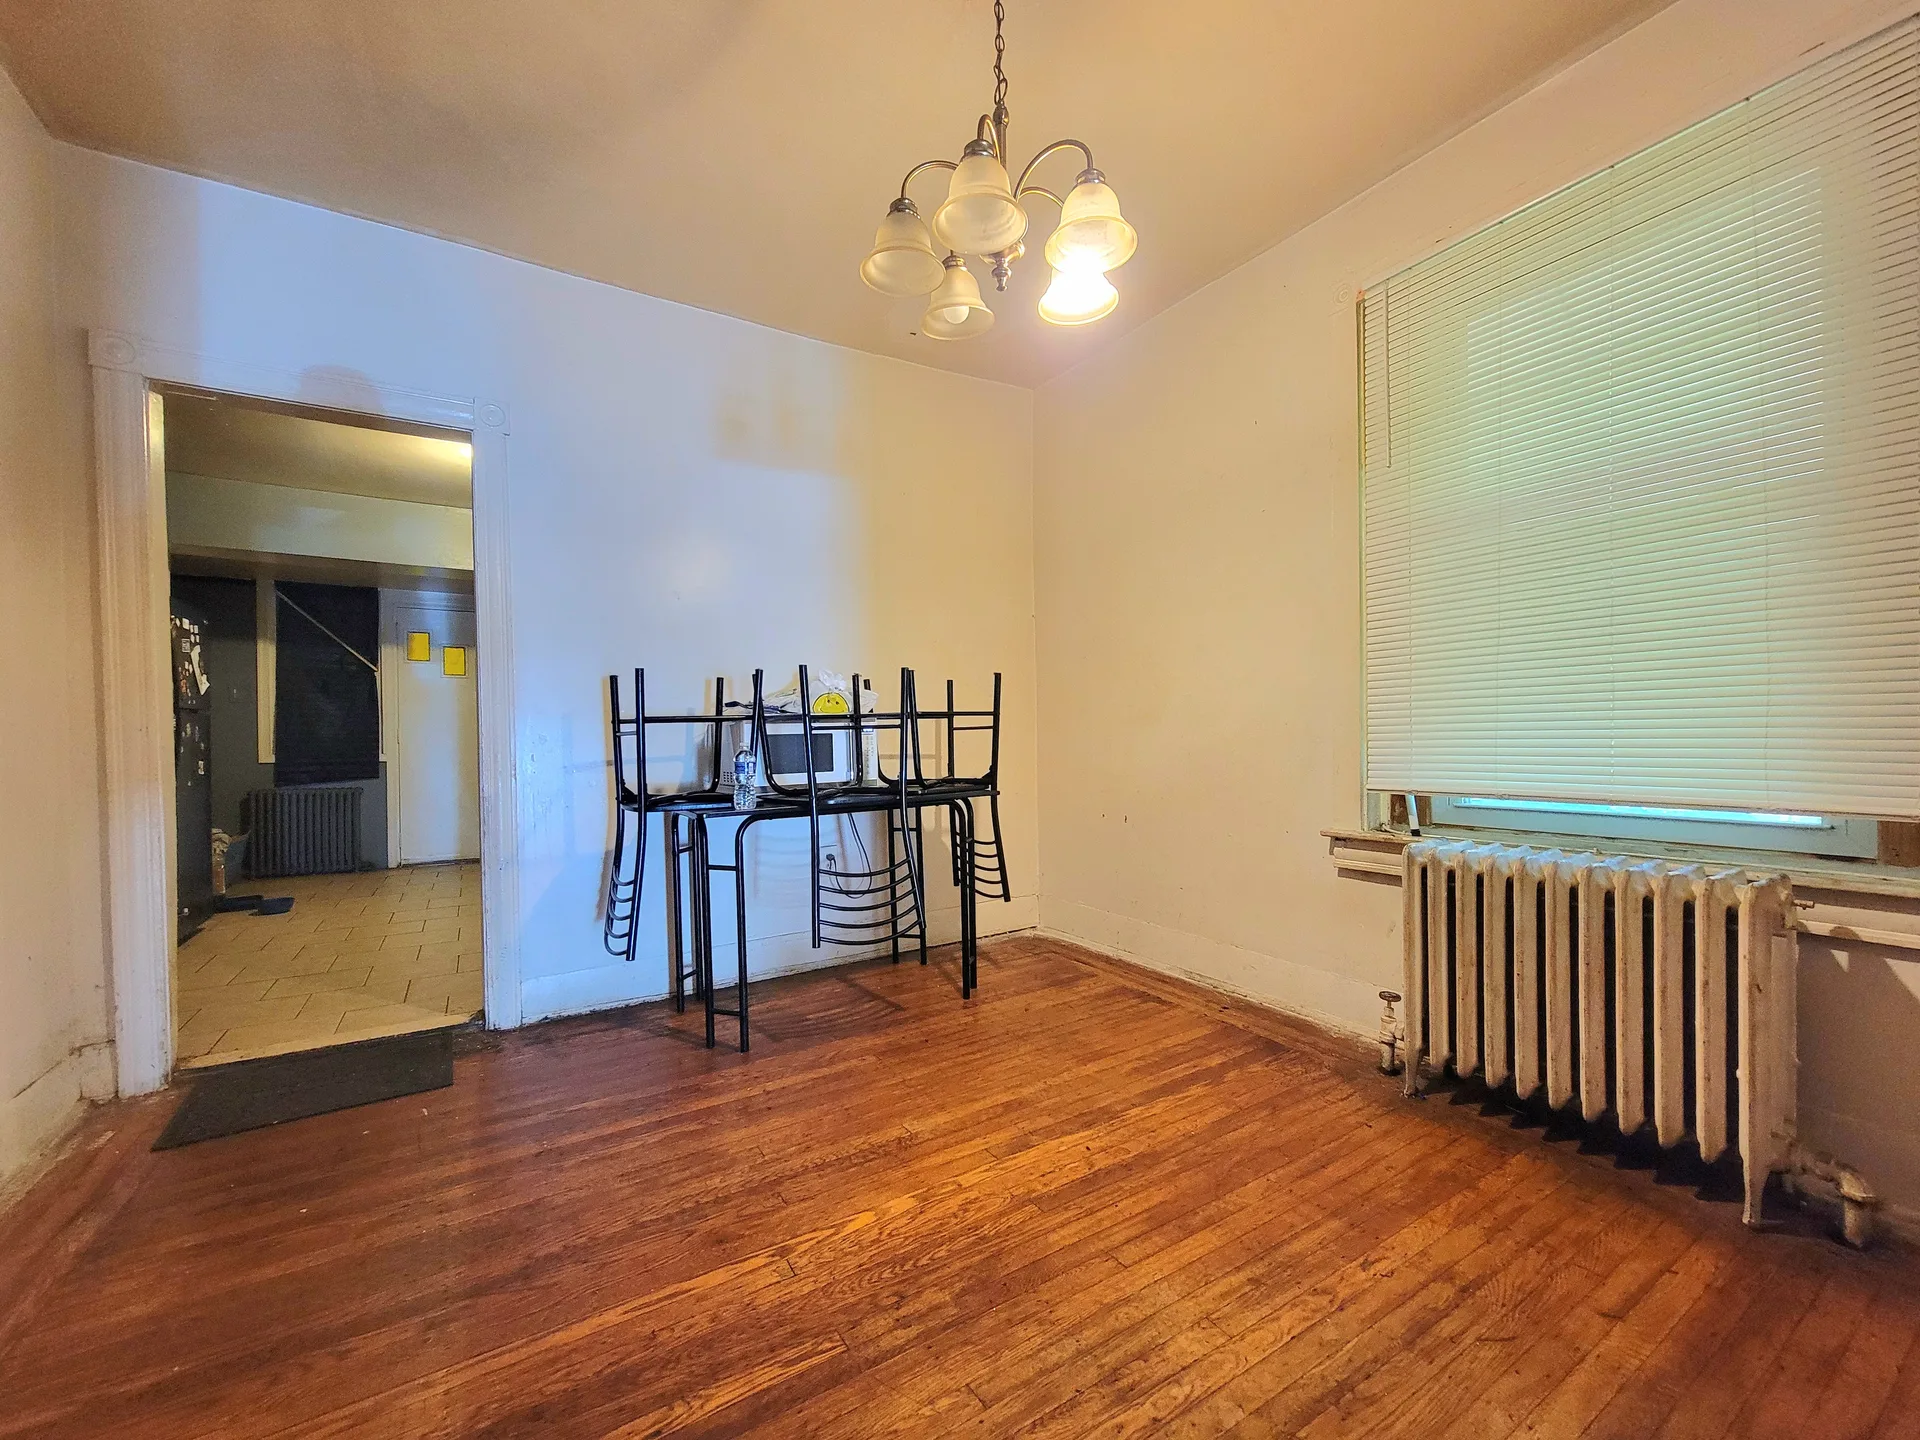
Dining room with hardwood floors, white walls, and a cast-iron radiator in a traditional Philadelphia row home, the housing style common across Bustleton
Stop Foreclosure

Does the Lender Have to Prove They Own My Bustleton Mortgage Before Foreclosing in Philadelphia?

Yes. In Pennsylvania, foreclosure is a judicial process, so the lender must prove it actually owns your Bustleton mortgage note and has the right to foreclose before a Philadelphia sheriff sale can be scheduled. The promissory note, not the mortgage, is the document that carries the debt, and a lender that cannot show it holds the note has not yet met its burden.

If you live in Bustleton, in the Far Northeast near Pennypack Creek and the Red Lion Road corridor, and a foreclosure case is working its way through the Court of Common Pleas, you may have heard that the lender has to prove it owns the mortgage. That is not a rumor, it is one of the real defenses available to a Pennsylvania homeowner. Understanding how it works, and what it can and cannot do for you, is part of knowing your options.

Why Does the Lender Have to Prove It Owns the Note?

Pennsylvania foreclosures are judicial, which means the lender cannot simply take your Bustleton home. It must file a complaint in mortgage foreclosure in the Court of Common Pleas, prove its case, and obtain a judgment before a Philadelphia sheriff sale can even be scheduled. To do that, the foreclosing party must have standing, which means it must show it is the holder of your promissory note, or an assignee in possession of a properly endorsed note. The note is the dispositive document. The mortgage follows the note, so whoever holds the note holds the right to enforce the debt.

What Happens If the Lender Can't Produce the Note or the Assignment?

If the lender cannot produce the original note or a valid assignment or endorsement, a homeowner who raises lack of standing in a written answer can force the lender to prove ownership. If it cannot, the court can dismiss the foreclosure action. And without a judgment of foreclosure and a writ of execution, there can be no sheriff sale. This is a real defense, but it is not a magic wand. It is one tool among several, and it depends on the facts of your case and how you respond in court.

How Do I Raise Lack of Standing on My Bustleton Home?

Standing must be raised, and the way to raise it is to respond to the foreclosure complaint. In Philadelphia, filing a written answer within 20 days of service prevents a default judgment, which is the step that keeps your case alive. If you do not answer, the lender can obtain a default judgment and move toward a sheriff sale without ever having to prove ownership. This is why acting early, and having the right help, matters so much. Free help is available through the Save Your Home Philly Hotline, run by the City of Philadelphia and Philadelphia Legal Assistance.

What If a Sheriff Sale Is Already Scheduled for My Bustleton Home?

Standing is decided before the sale, not at it. Once a sale date is set, the Philadelphia Sheriff's Office conditions of sale provide that a scheduled sale will not be stopped unless the Sheriff's Office is contacted by the attorney on the writ, by court order, or at the direction of the court. In practical terms, a homeowner contesting standing generally needs a court order to halt the sale. Filing a petition with the Court of Common Pleas to stay or postpone the sale can buy time, and it postpones rather than cancels the auction. A sale of the home, a short sale, or catching up the arrears are the routes that end the process entirely.

What Should a Bustleton Homeowner Do First?

The full plan for keeping your options open is laid out on the stop foreclosure help page for Bustleton. If selling before the sale date makes sense, a short sale in Bustleton with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender. And if your home has already been through a listing that did not sell, the expired listing help for Bustleton page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the wider set of protections is explained in Facing Foreclosure in Philadelphia? 6 Legal Protections Most Homeowners Don't Know About on the blog.

A lender's right to foreclose is a question of proof, and the proof must come before the sale. Call Andre at 267-977-0304 or book a free consult, and get a straight answer about where your Bustleton home stands and what to do next. You can also reach Andre through the contact page. Every conversation is confidential, and there is no judgment, only solutions.
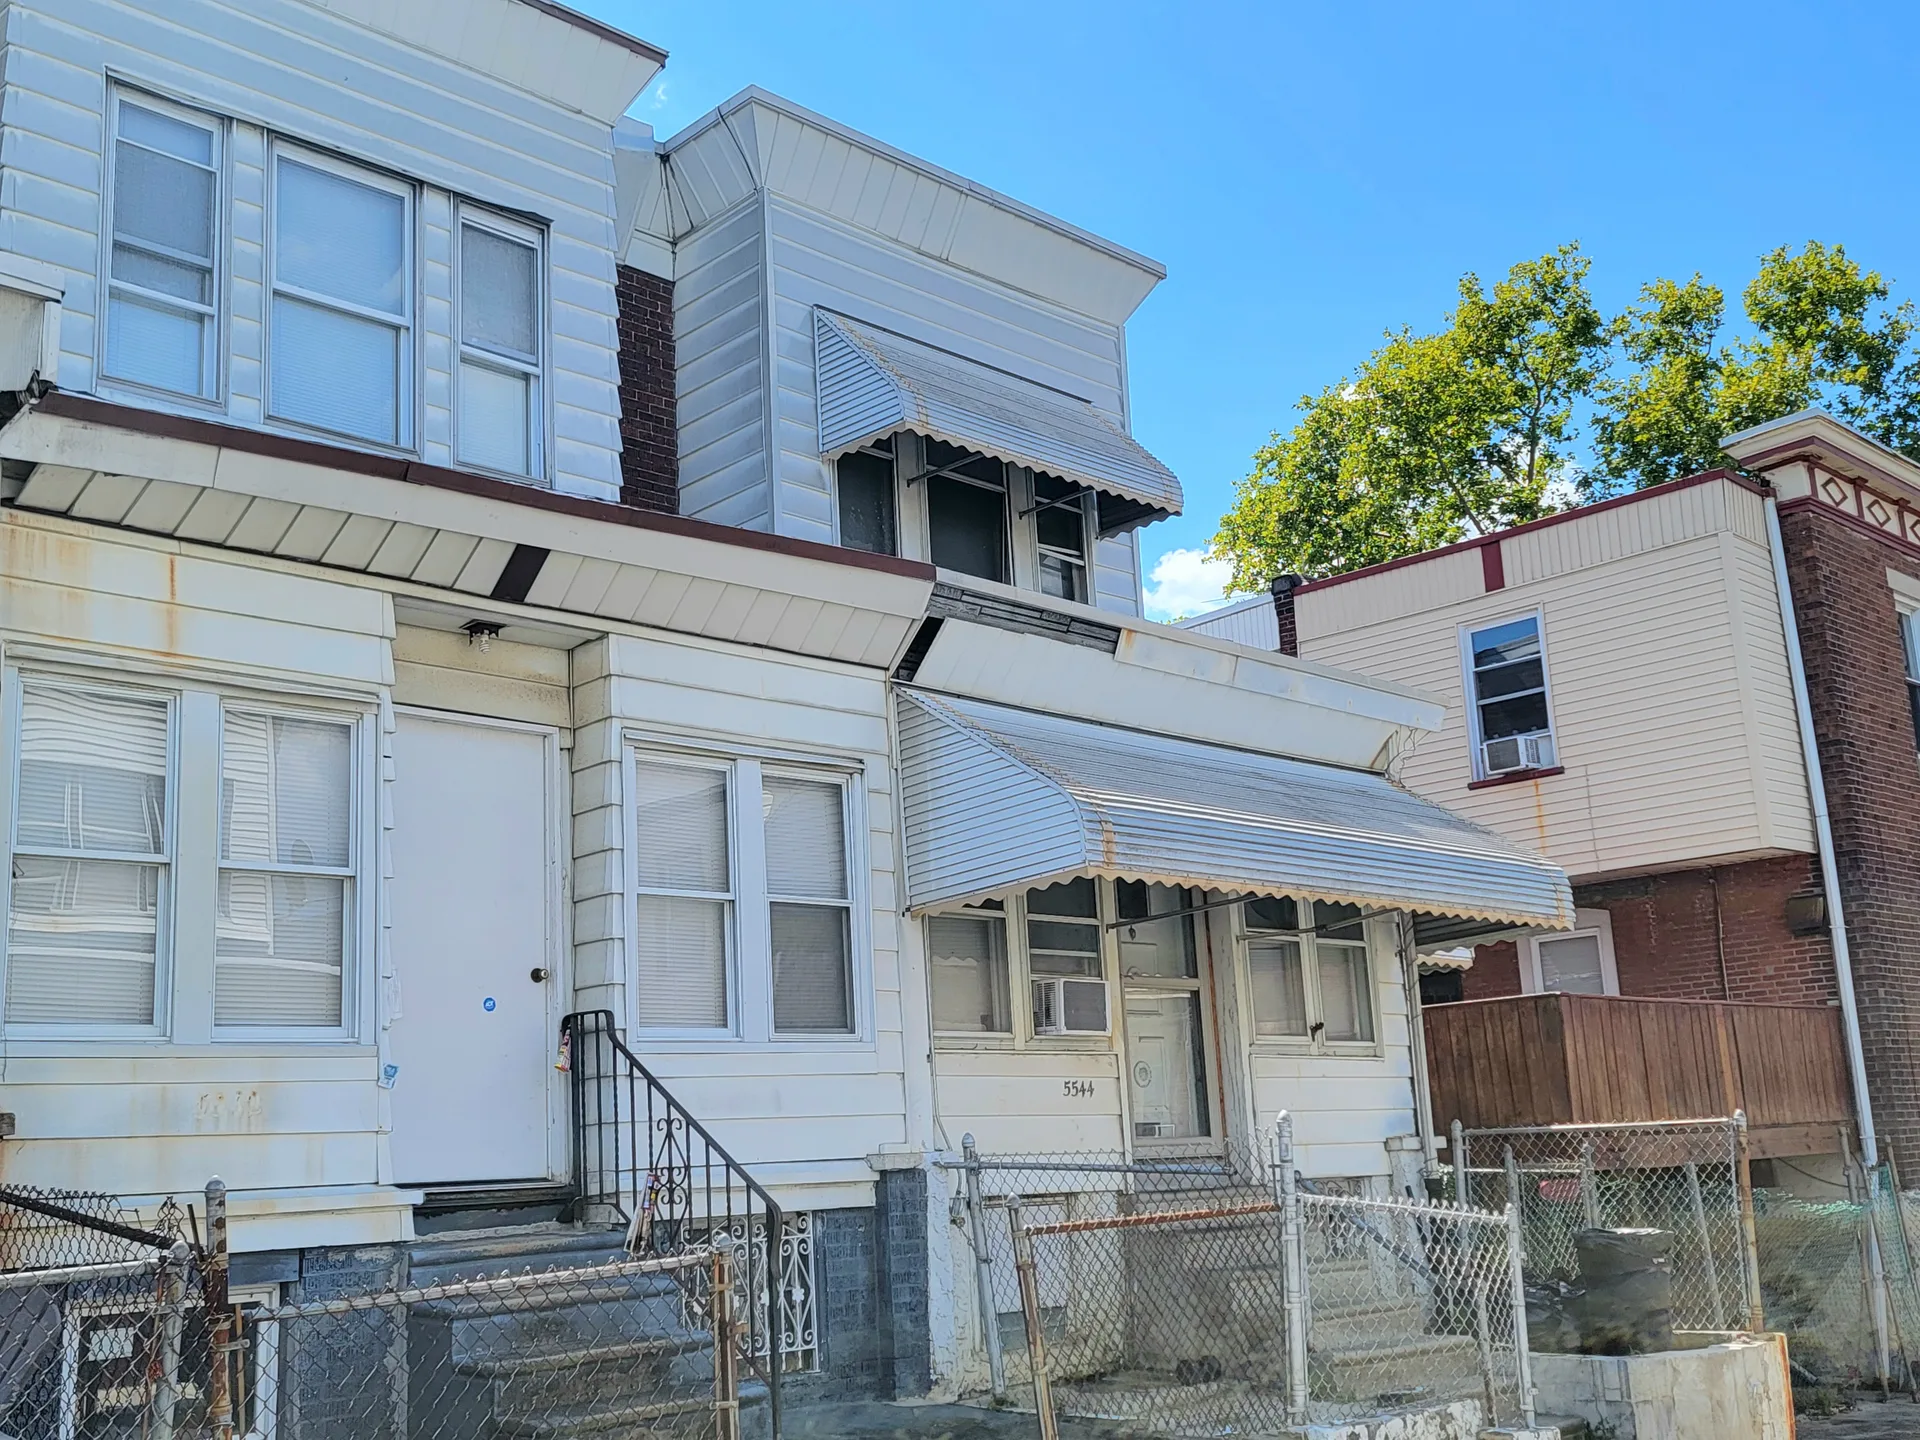
Front facade of a traditional Philadelphia row house with vinyl siding and a brick foundation, the housing style common across Bustleton
Stop Foreclosure

How Much Notice Will I Get Before a Sheriff Sale on My Bustleton Home in Philadelphia?

At least 30 days. Under Pennsylvania Rule of Civil Procedure 3129.2, the Philadelphia Sheriff's Office must post a handbill on your Bustleton property and send you written notice at least 30 days before the sale date. The notice names the property being sold, the court judgment behind the sale, and the amount needed to satisfy it, so you will not learn about the auction the day it happens.

If you live in Bustleton, in the Far Northeast near Pennypack Creek and the Red Lion Road corridor, and a foreclosure case is working its way through the Court of Common Pleas, the question that weighs on you most is often the simplest one: how much warning will I actually get before the sheriff sale? The answer sets the clock for every option you still have, and it is more generous than many homeowners expect.

What Does the 30-Day Sheriff Sale Notice Include?

Under Pa.R.C.P. 3129.2, notice of a Philadelphia sheriff sale is delivered three ways. The Sheriff's Office posts handbills in its office and on the property itself at least 30 days before the sale. Written notice is mailed to the parties named in the Rule 3129.1 affidavit at least 30 days before the sale. And the sale is advertised in a newspaper of general circulation. The handbill must describe the property, its location, any improvements, the judgment on which the sale is being held, and the amount required to satisfy the judgment.

Philadelphia holds sheriff sales monthly, and the auctions run online through Bid4Assets. The same properties appear on the list the Sheriff's Office publishes at phillysheriff.com, so you can check your own address against the schedule as soon as a sale date is set.

What Should I Do the Day the Notice Arrives?

The notice is a deadline, not a verdict. From the moment it arrives, you still have real options, and the 30-day window is exactly the time to use them:

  • Reinstatement. Pennsylvania's Act 6 protections let you cure the default at any time up to one hour before bidding begins at the sheriff sale, by paying the arrears plus reasonable fees and costs. In Philadelphia you can reinstate as late as one hour before the sale, up to three times in a calendar year.
  • A loan modification or a settlement with your lender can also take the property off the sale schedule. If speaking with the lender is the best route, he guides you to coordinate with your lender.
  • A Chapter 13 bankruptcy filing triggers an automatic stay that halts the sale, often the same day.
  • A sale of the home. A completed sale on the open market cancels the auction, because the mortgage is paid off at closing.

How Much Time Do I Have to Sell My Bustleton Home?

The 30-day notice is the final countdown, but it is rarely the whole story. In Pennsylvania, the foreclosure process typically runs six to twelve months from the first missed payment to the sheriff sale, with a 120-day federal waiting period before the lender can even begin formal proceedings. Philadelphia's Mortgage Foreclosure Diversion Program, which requires a conciliation conference, can extend that window further. Homeowners who list early use that time to capture the value Bustleton's brick rowhomes and twins hold, pay off the mortgage, and protect their credit. The earlier you act, the more of that value you keep.

What Happens If the Notice Comes and Nothing Changes?

The sale happens on the advertised date. The home is auctioned to the highest bidder, often the foreclosing lender itself, and Pennsylvania has no redemption period after a mortgage foreclosure sheriff sale, so the home cannot be bought back once the sale is confirmed. Because Pennsylvania is a recourse state, a deficiency judgment for the unpaid balance can follow as well. Every one of those outcomes is avoidable, but only with action before the sale date.

What Should a Bustleton Homeowner Do First?

The full plan for keeping your options open is laid out on the stop foreclosure help page for Bustleton. If selling before the sale date makes sense, a short sale in Bustleton with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If your home has already been through a listing that did not sell, the expired listing help for Bustleton page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the overall timeline is explained in How Long Before Foreclosure in Pennsylvania? on the blog.

The 30-day notice is not the end of your story, but the clock is moving. Call Andre at 267-977-0304 or book a free consult, and get a straight answer about whether your Bustleton home can stay in your family before the sale date. You can also reach Andre through the contact page. Every conversation is confidential, and there is no judgment, only solutions.
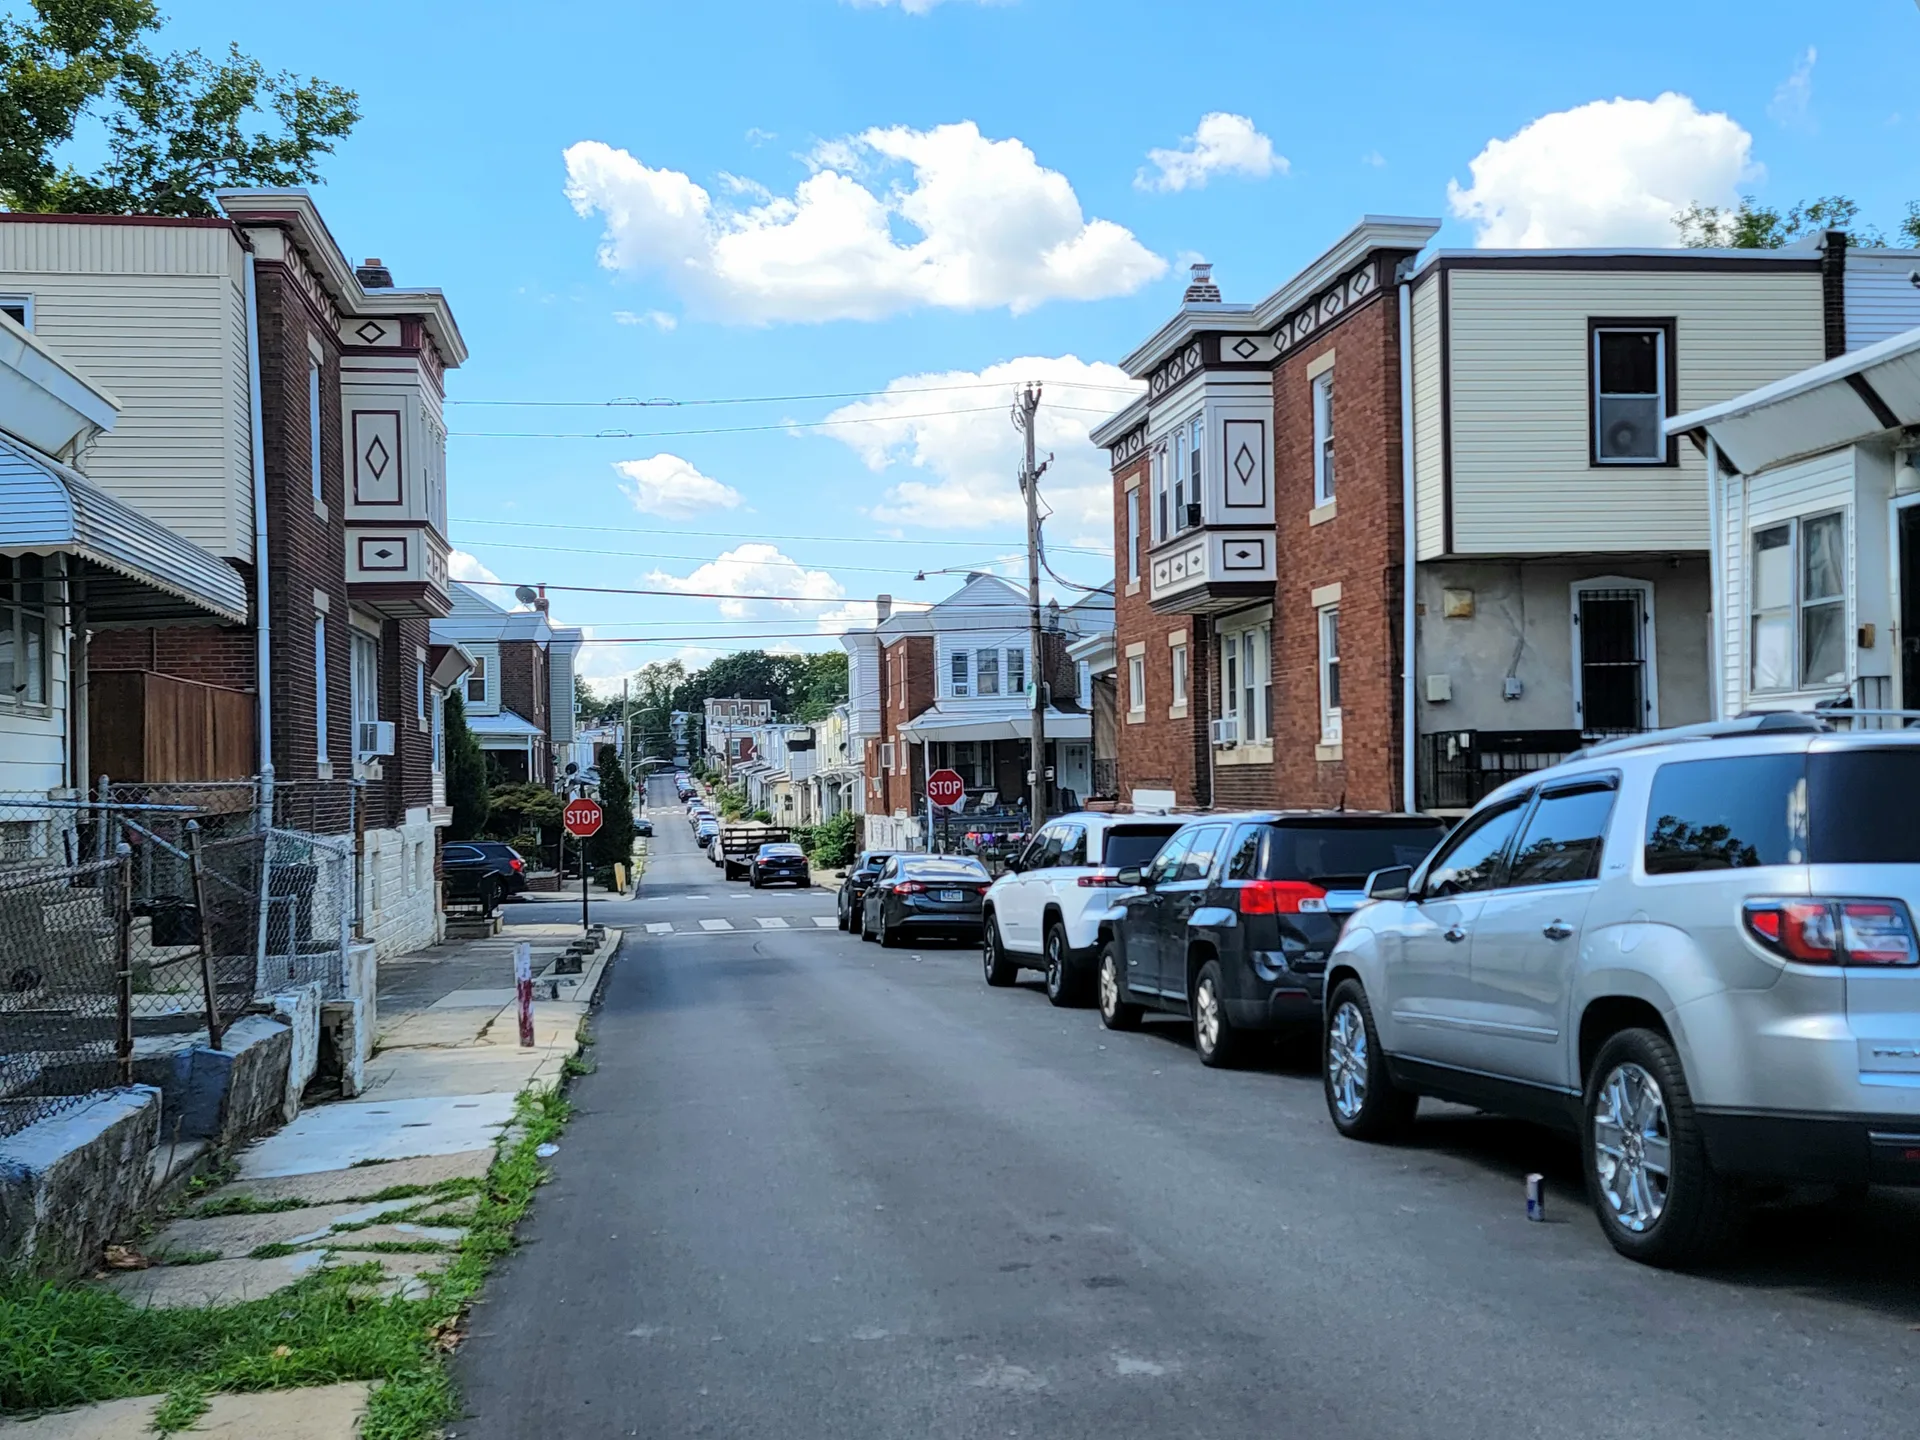
Residential street in Northeast Philadelphia lined with brick and siding rowhomes, the housing style common across Bustleton
Stop Foreclosure

What Happens to My Second Mortgage or HELOC If My Bustleton Home Sells at a Philadelphia Sheriff Sale?

Yes, the lien is wiped from the title but not the debt. When a Philadelphia sheriff sale is confirmed, the winning bidder takes your Bustleton home free and clear of the second mortgage or home equity line of credit (HELOC) attached to it, as long as that lender received proper notice of the sale. But removing the lien from the title does not erase the debt: the second lender can still pursue you personally for what you owe on that loan.

If you live in Bustleton, in the Far Northeast near Pennypack Creek and the Red Lion Road corridor, and you are facing foreclosure, one of the most confusing questions is what happens to the second mortgage or HELOC you took out years ago. Many Bustleton homeowners used a home equity line to pay for a new roof, a kitchen update, or tuition, and the idea of that loan surviving the foreclosure is frightening. Here is exactly what Pennsylvania law does with a junior lien at a sheriff sale, and what it means for you.

What Does "Free and Clear of Junior Liens" Mean for a Bustleton Home?

In Pennsylvania, a sheriff sale in a judicial mortgage foreclosure conveys the property free and clear of all junior liens, including second mortgages, home equity loans, and HELOCs, as long as the junior lender received proper notice. The successful bidder takes title without that lien. Bustleton's post-war twins and rowhomes hold real value, and a sheriff sale can wipe out the equity that would have satisfied those loans in one morning.

Can the Second Mortgage Lender Still Collect After the Sheriff Sale?

Yes. Wiping the lien off the title does not wipe out the debt. The second mortgage or HELOC obligation survives as an unsecured debt, and the junior lender can still pursue you personally on the promissory note, by suing on the note and collecting like any other judgment creditor.

What About the First Mortgage and a Deficiency Judgment?

The rules differ for the first mortgage. In Pennsylvania, the foreclosing first lender must file a separate deficiency-judgment action within six months of the sale, under 42 Pa.C.S. Section 8103, to collect any shortfall. A second mortgage lender generally does not need that step, because its unpaid balance simply becomes an unsecured obligation it can collect directly.

Can Selling Before the Sheriff Sale Protect Me From the Second Mortgage?

This is where acting before the sale date matters most. A traditional sale that pays off both loans ends every claim against the home. A short sale requires every lienholder to agree to the terms, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender. Selling before the sale date also protects your credit far more than a completed foreclosure.

What Should a Bustleton Homeowner With a Second Mortgage Do First?

Pull out your loan statements and find out who holds each lien, then get a clear picture of what is owed on both loans. The full plan for keeping your options open is laid out on the stop foreclosure help page for Bustleton. If selling before the sale date makes sense, a short sale in Bustleton with every lender's approval can end the threat of foreclosure. And if your home has already been through a listing that did not sell, the expired listing help for Bustleton page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the mechanics of deficiency judgments are explained in Will You Still Owe Money After Foreclosure in Pennsylvania?

A second mortgage does not have to cost you the home. Call Andre at 267-977-0304 or book a free consult, and get a straight answer about both loans before the sale date. You can also reach Andre through the contact page. Every conversation is confidential, and there is no judgment, only solutions.

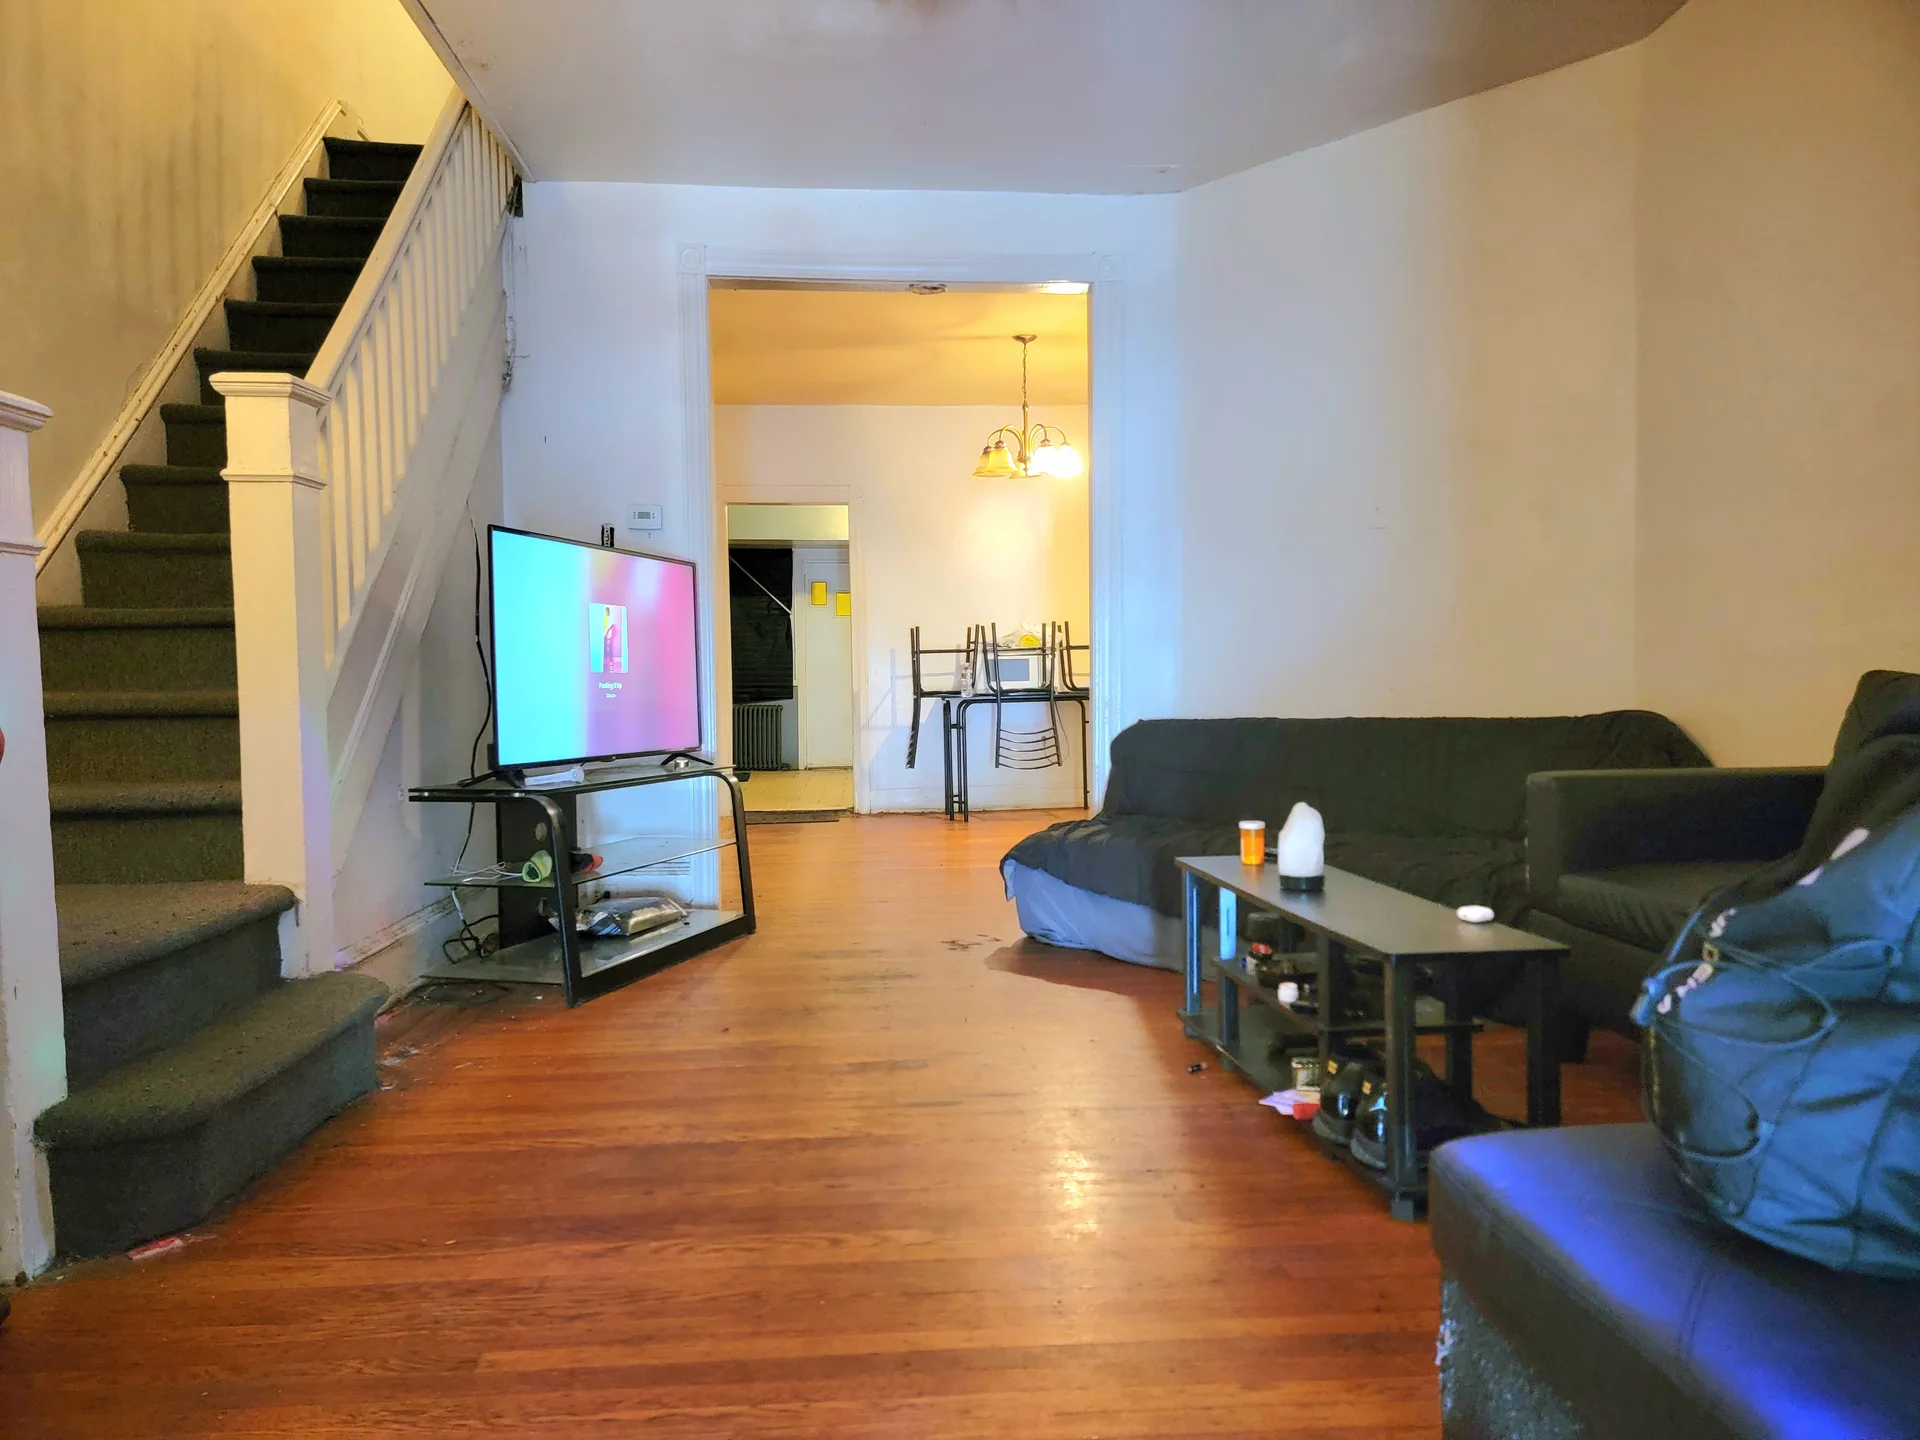
Living room interior with hardwood floors and a staircase in a Northeast Philadelphia-style row home
Stop Foreclosure

Is My Bustleton Home on the Philadelphia Sheriff Sale List?

Yes. If a Philadelphia foreclosure judgment has been entered against your Bustleton home, your property will appear on the monthly sheriff sale list that the Philadelphia Sheriff's Office publishes at phillysheriff.com, and the same properties are advertised in The Legal Intelligencer. The list is the official record, and every property on it carries a book and writ number, so you can check your own address against it directly.

If you live in Bustleton, in the Far Northeast near Pennypack Creek and the Red Lion Road corridor, and you have fallen behind on your mortgage, one of the most stressful unknowns is whether your home will end up on the sheriff sale schedule. Homeowners across Philadelphia ask this constantly, and the Sheriff's Office itself counts finding the most accurate list among its most common questions. Here is how to find out for certain, and what to do the moment you know.

Where Is the Official Philadelphia Sheriff Sale List Published?

Philadelphia holds sheriff sales monthly, and the auctions are conducted online through Bid4Assets.com. Before each sale, the Sheriff's Office publishes the list of properties the Court of Common Pleas has ordered sold on its website, on the List of Properties page at phillysheriff.com. The same properties are advertised in The Legal Intelligencer and in a paper of general circulation. Each entry is tied to a book and writ number, so when you find your street address on the list, write down the sale date and that number, because it is the reference lenders and attorneys use.

How Do I Know the List Has My Property and Not Someone Else's?

Pennsylvania foreclosures are judicial, which means your case runs through the Court of Common Pleas before any sale can be scheduled. Along the way you should have received the Act 91 notice required at the start of the process, and the case papers tell you where things stand. But notices can be missed and addresses can be mixed up, so the published list is the check that matters. If a sale date exists for your Bustleton home, your address will be on it; if the case was settled, postponed, or dismissed, it should not be.

What Happens If Nothing Changes Before the Sale Date?

The sale happens on the advertised date unless someone changes it. The home is auctioned to the highest bidder, often the foreclosing lender itself, and Pennsylvania has no redemption period after the sale, so the house cannot be bought back once the auction is confirmed. Bustleton's post-war twins and rowhomes hold real value, and a sheriff sale can wipe that equity out in one morning. Because Pennsylvania is a recourse state, a deficiency judgment for the unpaid balance can follow as well. Every one of those outcomes is avoidable, but only with action before the sale date.

What Can Take a Bustleton Home Off the Sale List?

The Sheriff's Office will not pull a property off the list on its own. Per the published conditions of sale, the sale proceeds unless the attorney on the writ asks to remove it, a court order halts it, or the Sheriff's Office exercises its discretion. Homeowners have real routes to make that happen:

  • Reinstatement. Pennsylvania's Act 6 and Act 91 protections let you catch up the missed payments and fees, and in Philadelphia you can reinstate as late as one hour before the sheriff sale, up to three times in a calendar year.
  • A sale of the home. A completed sale on the open market, whether a traditional sale or a short sale, satisfies the process and cancels the auction.
  • A court order. Filing a petition to postpone the sale through your attorney can push the date back and buy negotiating room.
  • Bankruptcy. Filing Chapter 13 or Chapter 7 triggers an automatic stay under federal law, 11 U.S.C. Section 362, that halts the sale, often the same day.
  • Lender coordination. The lender's attorney is the one who can remove a property from the sheriff sale list, so a direct conversation with your lender can matter more than anything else.

What Should a Bustleton Homeowner Do First?

Start by checking the current list at phillysheriff.com, then decide what you want the next chapter to look like. Andre Richardson has 26 years of experience in Philadelphia real estate, and he helps Bustleton homeowners sort through these exact choices. The full plan for keeping your options open is laid out on the stop foreclosure help page for Bustleton. If selling before the sale date makes sense, a short sale in Bustleton with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender. And if your home has already been through a listing that did not sell, the expired listing help for Bustleton page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia.

If your address is on the Philadelphia sheriff sale list, this is not the end of your story, but the clock is moving. Call Andre at 267-977-0304 or book a free consult, and get a straight answer about whether your Bustleton home can stay in your family before the sale date. You can also reach Andre through the contact page. Every conversation is confidential, and there is no judgment, only solutions.

Your Bustleton home
is worth protecting.

Let's talk about your options, on your timeline.

Want to know what your home is worth? Get a real valuation of your home's value.

Licensed. Local. Legit.

Pennsylvania License RS349905 · New Jersey License 1969348
HomeSmart Realty Advisors

Experience. Strategy. Results.

267-977-0304

Need more room to move? Read the full foreclosure and short sale guidance for Philadelphia, see expired listing help in Bustleton if your home has already been through a listing that didn't sell, or contact Andre directly.