Can I Sell My East Oak Lane Home If I Have a Second Mortgage or HELOC in Philadelphia?
Yes, you can sell your East Oak Lane home before the Philadelphia sheriff sale even if you have a second mortgage or a home equity line of credit (HELOC). Pennsylvania law does not stop you from selling during the foreclosure process, and you own the home until the sheriff sale is completed and title transfers. The second lien does not block the sale, but it has to be paid off or released at closing, and the sale has to close before the sheriff sale date.
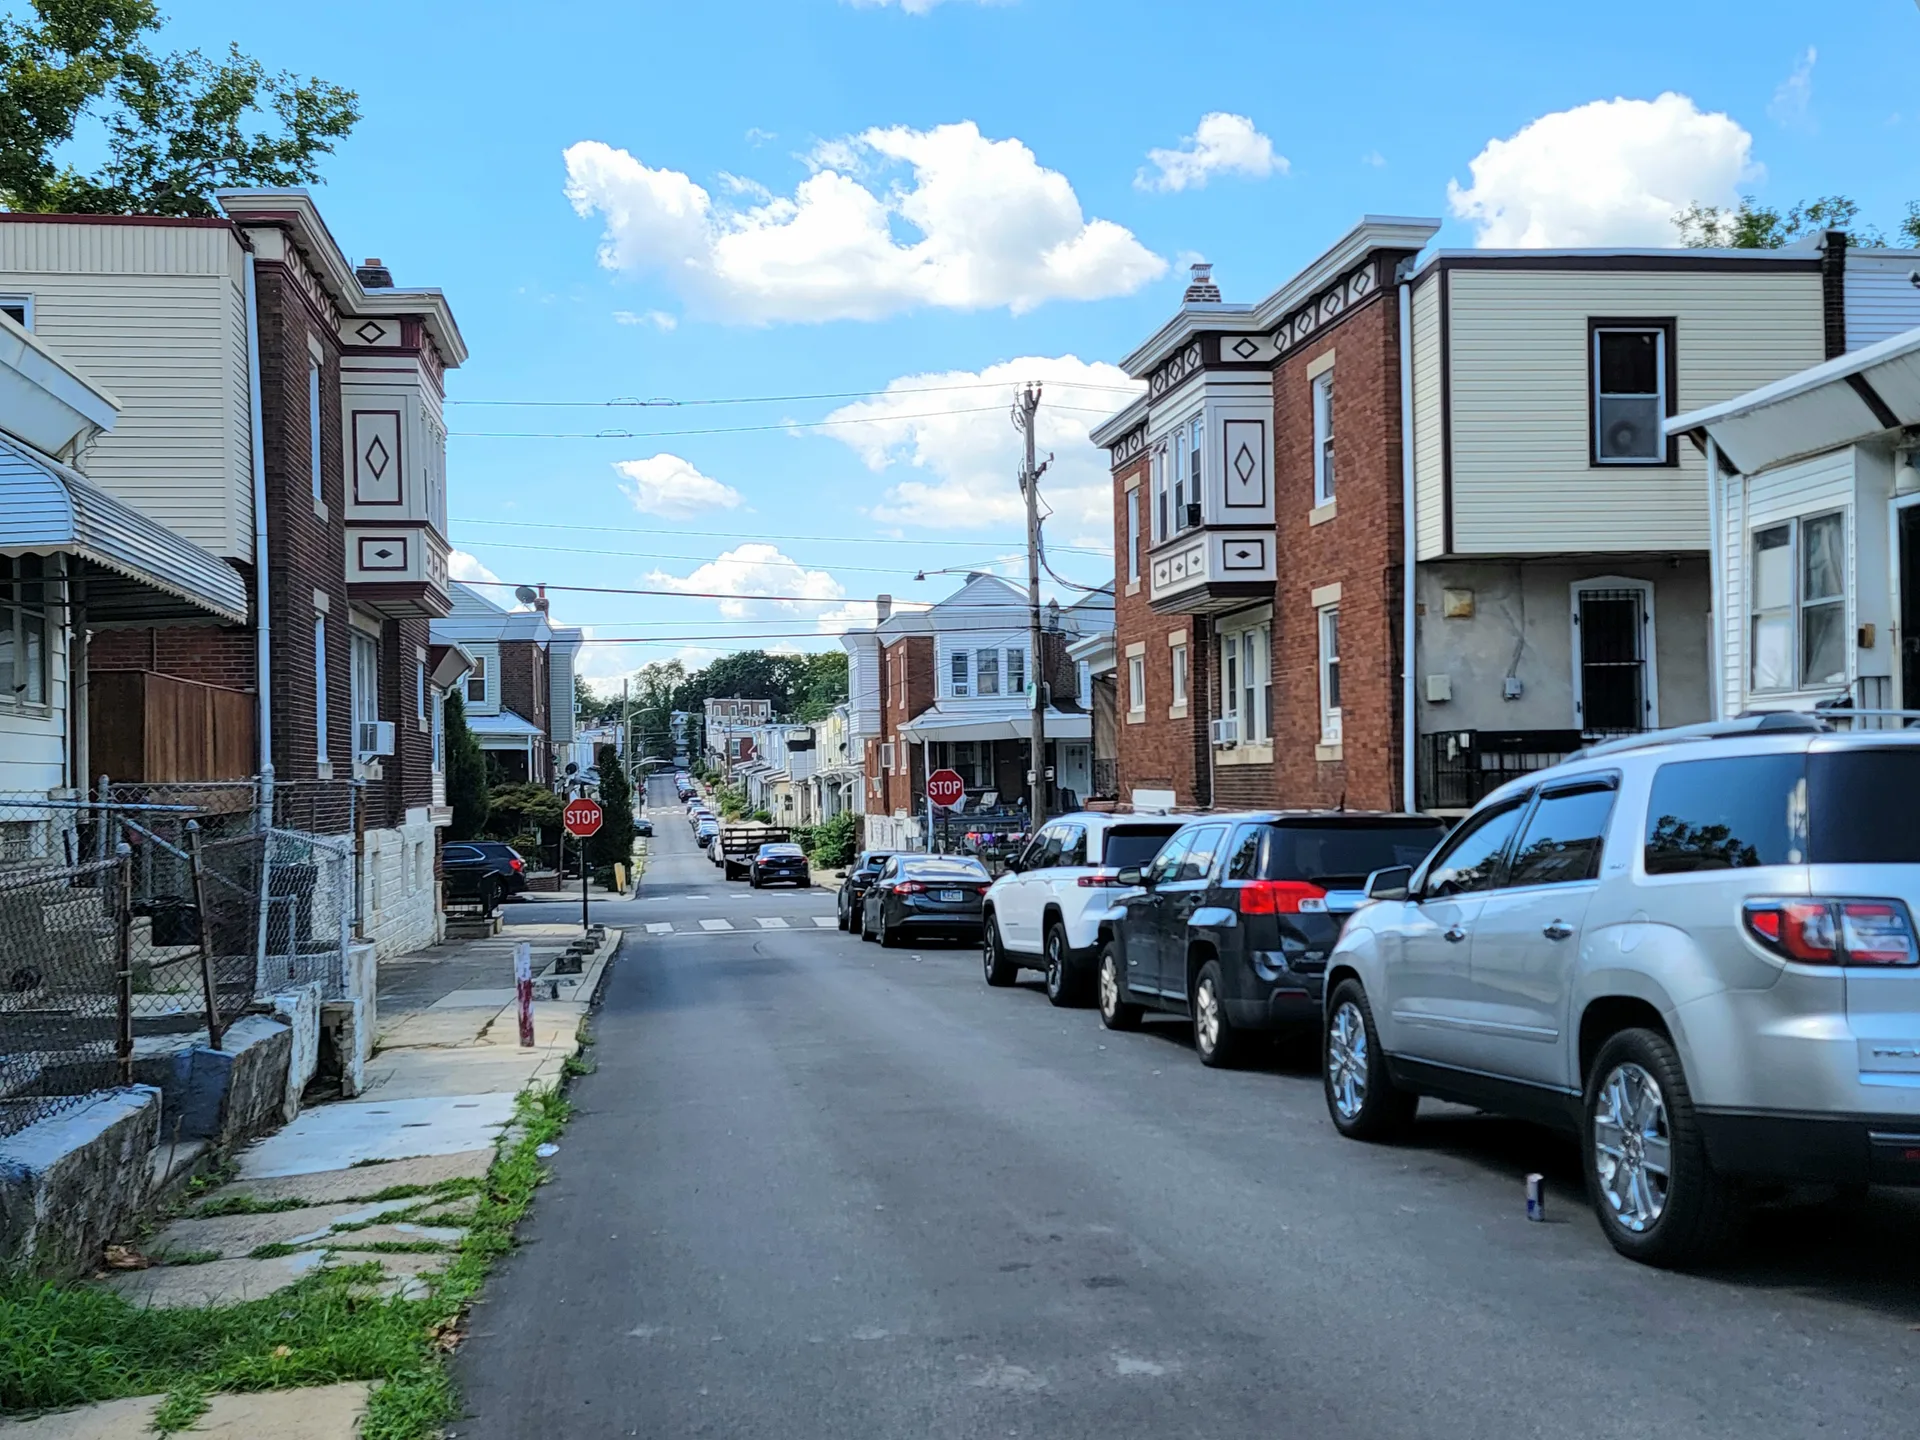
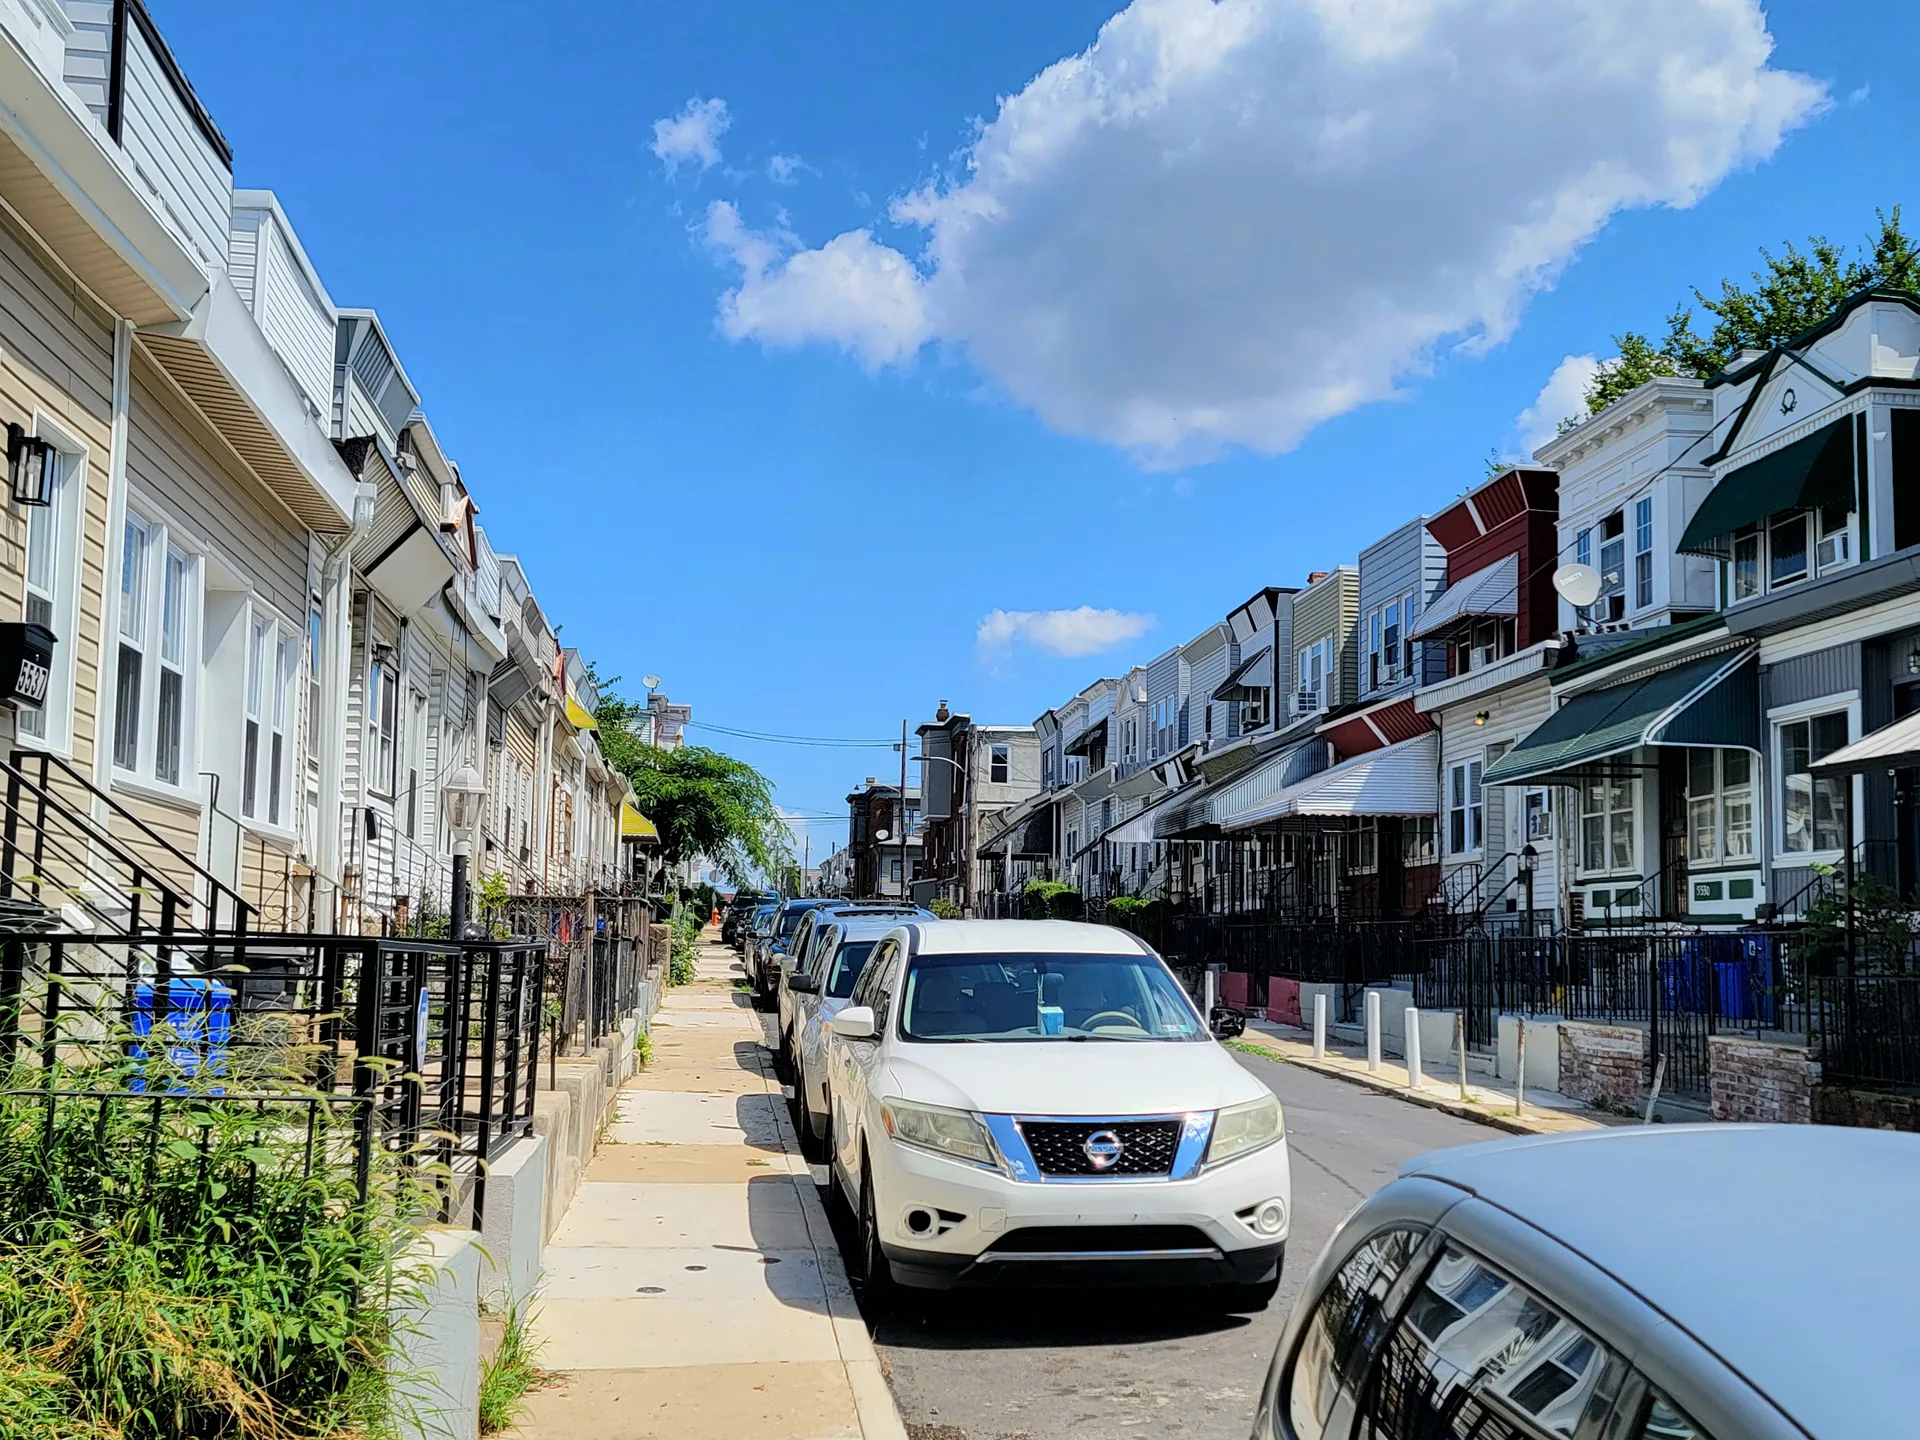
If you live in East Oak Lane, the stretch of stone twins and large single-family homes on tree-lined streets at the northern edge of Philadelphia, and you are facing foreclosure with a second mortgage or HELOC on top of your first loan, you may have assumed selling was off the table. It is not. The question is not whether you can sell, but how the second lien gets handled so the sale can actually close in time.
Can You Sell a Home With a Second Mortgage or HELOC During Foreclosure in Pennsylvania?
Yes. You hold title to your East Oak Lane home until the sheriff sale is completed, and Pennsylvania law does not prevent you from selling at any point during the foreclosure process. A second mortgage or HELOC is a lien on the property, not a block on the sale. The home can be sold while the second loan exists, as long as the lien is dealt with at closing.
What Happens to the Second Mortgage or HELOC at Closing?
At closing, the title company pays off the liens on the property in order of priority: the first mortgage first, then the second mortgage or HELOC. The second lender has to release its lien before title can transfer to the buyer. If the sale price covers both loans, the second loan is simply paid in full from the proceeds. If there is not enough to pay both, the situation becomes a short sale, and every lienholder has to approve the sale.
What If the Sale Price Won't Cover Both Loans?
If your East Oak Lane home is worth less than what you owe on the first and second loans together, a traditional sale will not work on its own. The sale becomes a short sale, and the second lien holder has to agree to accept less than it is owed. All lienholders must approve the short sale, and the first lender typically will not pay more to satisfy the second. This is where an experienced negotiator matters, because getting the second lender to release its lien is often the difference between a sale that closes and one that falls apart.
How Much Time Do You Have?
The sale has to close before the sheriff sale date, or the sale has to be postponed. Philadelphia sheriff sales are held monthly, and the foreclosure process in Pennsylvania typically runs six to twelve months from the first missed payment, with the court steps and Philadelphia's Mortgage Foreclosure Diversion Program adding time you can use. But the calendar moves faster than most homeowners expect, so the earlier you start, the more room you have to satisfy the second lien and close on time.
What Are Your Options in East Oak Lane?
With equity in your home, selling before the sheriff sale is often the path that protects the most value, and the second mortgage is handled in the normal course of closing. If you owe more than the home is worth, a short sale with the approval of every lienholder can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.
A second mortgage does not have to keep you trapped in a foreclosure, but the clock is moving. Andre Richardson has 26 years of experience in Philadelphia real estate, and he helps East Oak Lane homeowners sort through these exact choices. The full plan for keeping your options open is laid out on the stop foreclosure help page for East Oak Lane. If selling before the sale date makes sense, a short sale in East Oak Lane with the lender's approval can end the threat of foreclosure. And if your home has already been through a listing that did not sell, the expired listing help for East Oak Lane page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the financial side is explained in what happens with deficiency judgments in Pennsylvania. Call Andre at 267-977-0304 or book a free consult, and get a straight answer about your second mortgage and your East Oak Lane home. Every conversation is confidential, and there is no judgment, only solutions.