Stop foreclosure help in Roxborough, Philadelphia with Andre Richardson, Realtor — the go-to agent for foreclosure help in Roxborough
Stop Foreclosure

Foreclosure Help
in Roxborough

You have more options than you think.

Roxborough sits on its hilltop above the river valley, a close-knit community of brick rowhomes and twins where many owners have lived for decades and built real equity along the way. For most Roxborough homeowners, the house is the largest asset they own, and the value of staying put and holding on has worked in their favor. I'm Andre Richardson, and for 26 years I've been involved with Philadelphia real estate. Facing foreclosure doesn't mean your story is over. It means it's time to look at your options, and the earlier you do, the more choices you have.

26 Years
Real Estate Experience
5.0
Rating from 27 Reviews
AI
Powered Marketing
PA & NJ
Licensed
01
Why It Matters

Why Acting Early Matters
in Roxborough

A hilltop community looking out over the river valley, Roxborough is built on brick rowhomes and twins where homeowners have put down roots for decades. For most Roxborough homeowners, the house is the largest asset they own, and years of steady ownership have built equity that is very real. When a mortgage becomes hard to keep up with, that equity is exactly what makes acting early matter.

  • The earlier you act, the more options you have: a repayment plan, forbearance, a loan modification, a short sale, or a sale at full market value
  • Roxborough's hilltop location and longtime community identity keep a committed pool of buyers, which works in your favor when you need to sell on a timeline
  • Time protects equity: every month spent waiting narrows the gap between what you owe and what your home is worth
  • Solutions like a loan modification are far easier to secure before the process moves deep into the courts

Foreclosure in Pennsylvania is a judicial process, which means it moves in stages and there is a path forward at every stage. The mistake homeowners make is waiting to find it. The homeowners who call early keep control of the outcome, and in Roxborough, where decades of ownership built the equity, early action is how that equity gets protected.


02
Your Options

Options Beyond Foreclosure,
with Someone on Your Side

You have more options than you think. Each path below is a real, workable route, and every one of them goes better with Andre Richardson leading the way. He listens to your situation first, then builds the plan around your lender and your timeline.

Working with your lender

Before anything else, there may be room to work directly with your mortgage servicer: a repayment plan to catch up on missed payments, a forbearance that pauses payments for a set period, or a reinstatement agreement. Andre reviews your specific situation, and if speaking with your lender is the best route, he guides you to coordinate with your lender.

A loan modification

A loan modification rewrites the terms of your mortgage so the payment fits your current income, through a lower rate, a longer term, or added arrears. Modifications are far more attainable early in the process, and Andre will point you to talk with your lender.

A professionally guided short sale

If you owe more than the home can sell for, a short sale lets you sell with the lender's approval and walk away from the threat of foreclosure. Andre manages the entire negotiation for you, from the loss mitigation department to the paperwork, and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

Selling before foreclosure

If your Roxborough home holds equity, selling on the open market before the sheriff sale is often the strongest path. You capture the value your home has built, pay off the mortgage, protect your credit, and close the chapter on your terms, with Andre's aggressive AI-infused marketing working towards getting your home sold.

These paths are explained step by step in the full foreclosure and short sale guidance for Philadelphia, covering timelines, credit impacts, and lender negotiations. If the mortgage weighs more than the home can carry, the short sale guidance in Roxborough page walks through selling for less than you owe with the lender's approval. And if your home has already been through a listing that did not sell, the expired listing help in Roxborough page shows how a relaunch gets it sold. You do not have to choose a path alone.


03
The Agent

Why Sellers Trust Andre

By the time Roxborough homeowners facing foreclosure find me, many have been carrying the weight of the situation alone for months, and some have watched a previous listing fail. I bring 26 years of Philadelphia and South Jersey experience, active PA and New Jersey licenses, and a targeted marketing plan that gets homes sold. Every conversation is confidential, and there is no judgment, only solutions.

“Andre was very professional and knowledgeable, a definite credit to the profession. I would not hesitate to refer him to any of my friends or family for his real estate services. Andre did not hesitate to go above and beyond to make things happen. Job well done for me thank you Andre!”

— Stella Thompson, 5-star review

See how the sell my house process works or read the client reviews from sellers who started right where you are.


04
Answers

Questions Roxborough Homeowners
Facing Foreclosure Ask

Can I sell my Roxborough home after receiving a foreclosure notice?

Yes. You can sell at any point before the sheriff sale, and in Roxborough, where brick rowhomes and twins hold equity built over decades, selling before foreclosure is often the strongest path. A sale at or near market value lets you pay off the mortgage, keep what equity remains, and protect your credit. The key is starting now, because the timeline moves faster than most homeowners expect.

I've lived in my Roxborough home for decades. How do I sell before the sheriff sale date?

Selling before the sheriff sale works exactly like a traditional home sale, just with an urgent timeline. Andre prices the home honestly against the Roxborough market, markets it to the neighborhood's active buyer pool, and manages the offer and closing so the sale date happens before the court date. Decades of ownership usually mean meaningful equity, and that equity is what a timely sale protects.

How long does the foreclosure process take in Pennsylvania?

The foreclosure process in Pennsylvania typically runs six to twelve months from the first missed payment to the sheriff sale, and federal law requires a 120-day waiting period before a lender can even begin formal proceedings. Philadelphia's Mortgage Foreclosure Diversion Program, which requires a conciliation conference, can extend that window. For Roxborough owners with decades in their homes, that window is the time to turn equity into a choice.

Will a short sale protect me from the lender coming after the difference?

Pennsylvania is a recourse state, which means a deficiency judgment is possible after a foreclosure or a short sale unless it is waived. That is why the short sale agreement should include a deficiency waiver, a written provision that the lender will not pursue you for the remaining balance. Andre negotiates for that protection in every short sale he manages. A short sale also impacts credit far less than a completed foreclosure, and you can qualify for a new mortgage years sooner.

What happens if I do nothing?

If nothing changes, the process continues through the courts to a sheriff sale, where the property is sold at auction either to a private buyer or to the lender. You lose the equity in the home, your credit takes its hardest hit, and a deficiency judgment remains possible in Pennsylvania. That outcome is almost always avoidable, and the homeowners who call early keep the most control over how their story ends.

05
From the Blog

Roxborough Foreclosure
Advice

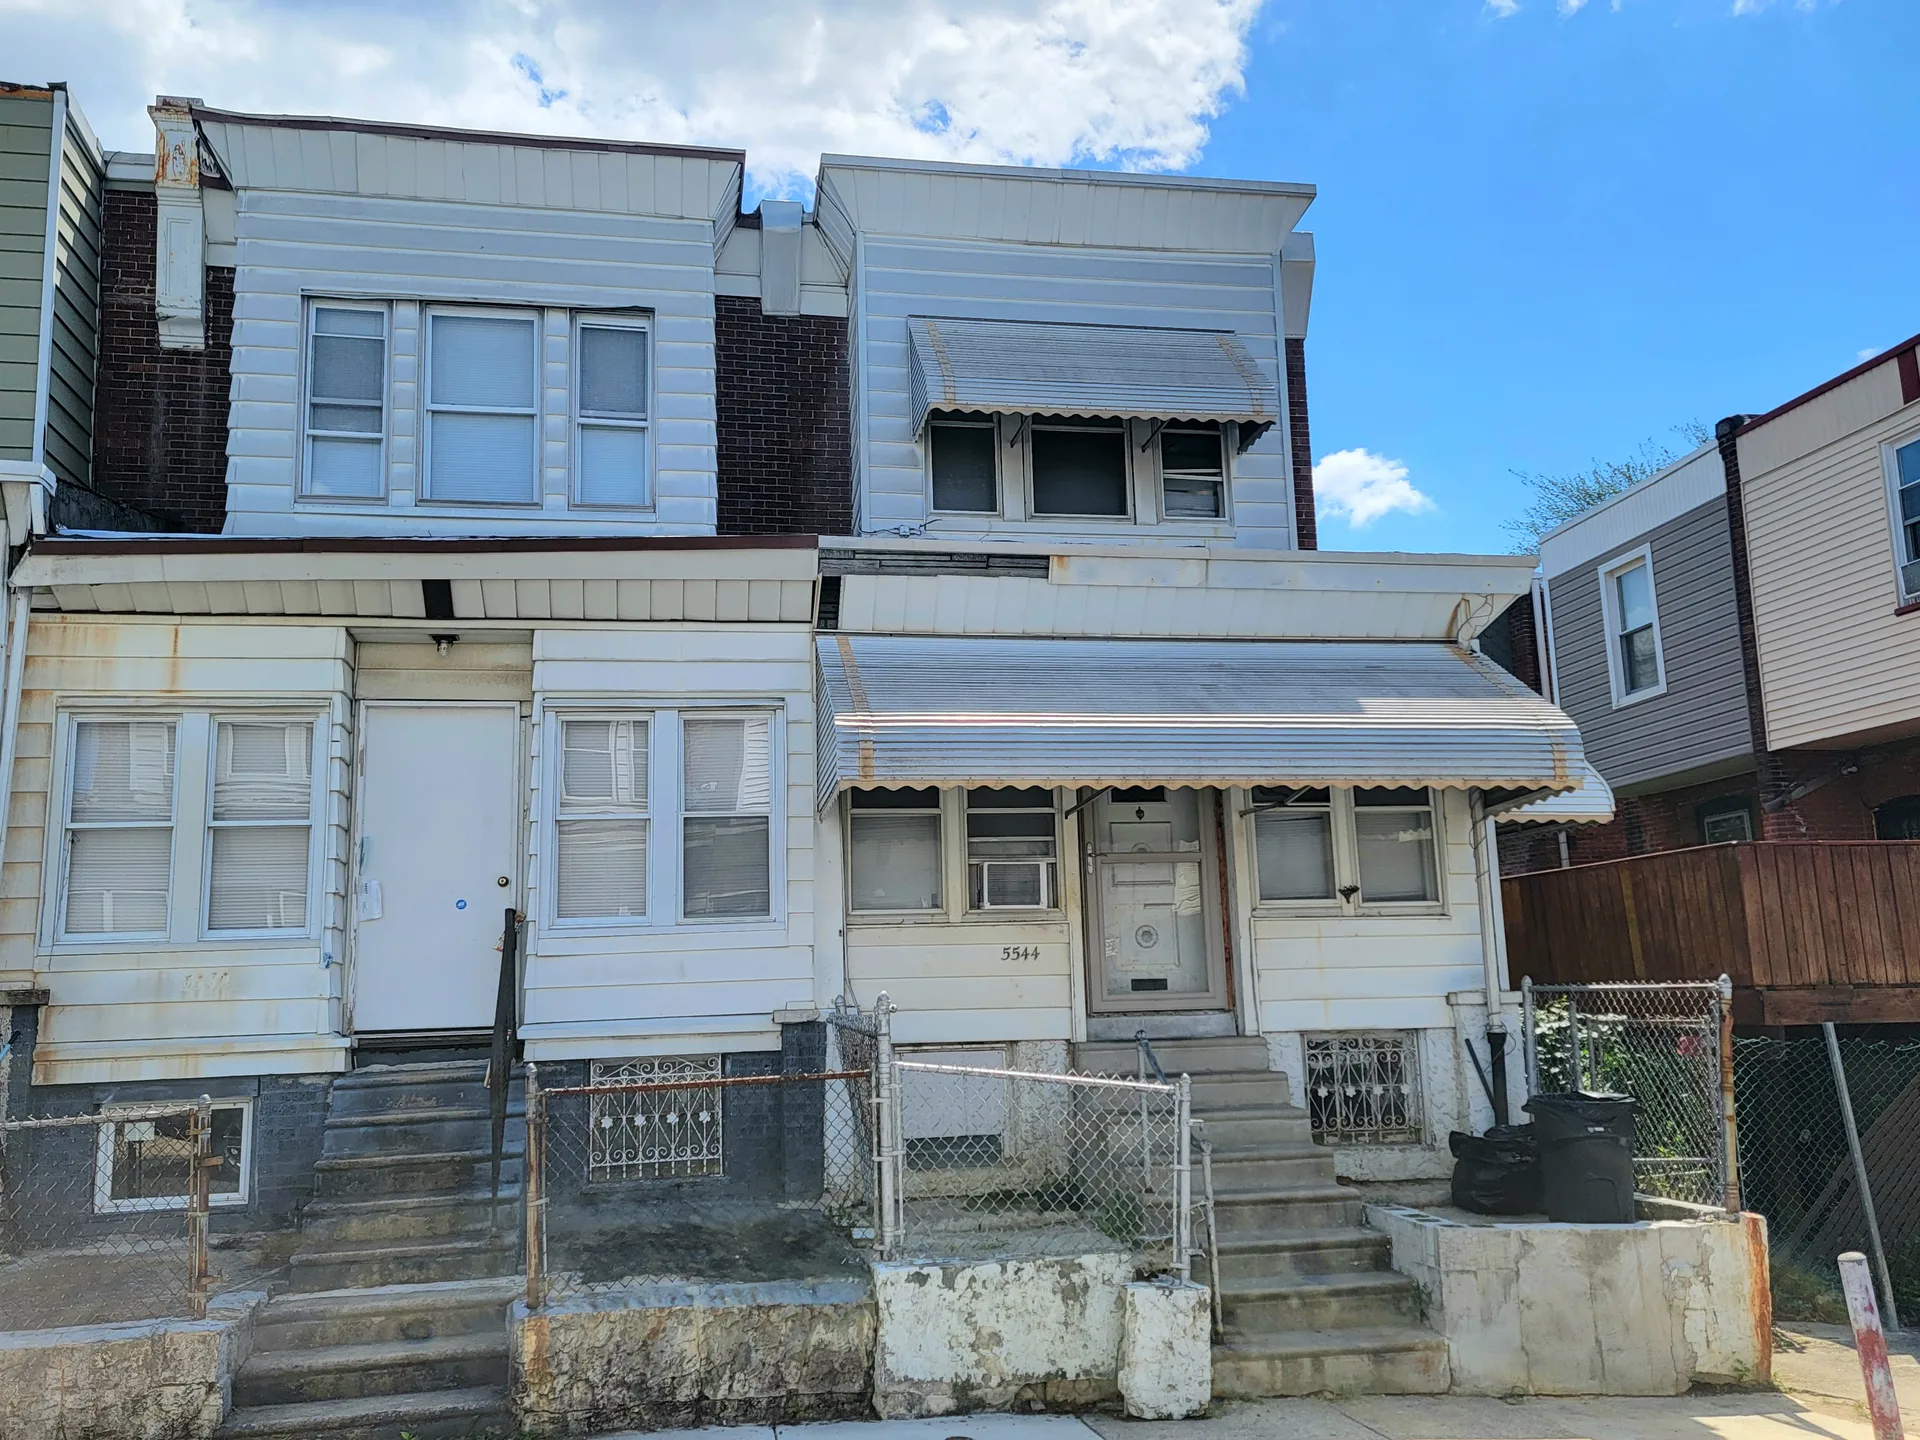
Two attached Philadelphia row homes with siding and stone foundations, the kind of twins and rowhomes found across Roxborough
Stop Foreclosure

Do I Need the Lender's Permission to Sell My Roxborough Home Before the Sheriff Sale?

No. In Pennsylvania, you own your Roxborough home until the Philadelphia sheriff sale actually transfers title, so you can sell it before the auction without the lender's permission, as long as the sale closes in time and pays off the mortgage in full. Lender approval is only required for a short sale, where the home sells for less than you owe.

If you live in Roxborough and a foreclosure case is moving through the courts, you may have heard that the bank owns your home once the lawsuit starts. That is not how Pennsylvania works. You hold title until the sheriff sale is completed, and that title is what lets you sell. For Roxborough homeowners who have lived on the hilltop above the river valley for decades, often in brick rowhomes and twins with real equity built up, selling before the sale date is one of the strongest ways to keep control of the outcome.

Do I need the lender's approval to sell my home during foreclosure?

No. Your mortgage is a lien on the property, not ownership of it. The lender's claim is against the debt, and the lien is paid off at closing from the sale proceeds. As long as the sale closes before the sheriff sale transfers title, you can list and sell your Roxborough home the same way you would in any other situation. The foreclosure case does not take your right to sell away; it just puts a deadline on it.

When does the lender's permission become necessary?

The one situation that changes is a short sale. If your Roxborough home is worth less than the mortgage balance, the sale price will not cover the loan, and the lender has to agree to accept the short payoff and release the lien. That approval is a formal negotiation with the lender's loss mitigation department. If speaking with the lender is the best route, he guides you to coordinate with your lender. For a sale at or near market value that pays the mortgage in full, no such approval is needed.

What happens to my mortgage when I sell before the sheriff sale?

At closing, the title company orders a payoff from your lender covering the remaining balance, the missed payments, and any fees the lender adds. The sale proceeds pay that amount, the lender releases the mortgage, and the foreclosure case is brought to an end. If the sale price leaves money after the payoff and closing costs, that surplus is yours. That is the equity you built while living in Roxborough, and a pre-sale sale is how it stays in your pocket instead of disappearing at auction.

What if the sale price doesn't cover the full mortgage balance?

If the home sells for less than you owe, the shortfall is called a deficiency, and Pennsylvania is a recourse state, which means the lender could pursue you for the difference unless it is waived. That is why a short sale agreement should include a deficiency waiver, a written provision that the lender will not come after you for the remaining balance. Andre negotiates the short sale for you and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

How do I sell my Roxborough home before the sheriff sale?

The mechanics are the same as any sale, with a compressed timeline: an honest read on the current value, a price that draws real offers, marketing aimed at buyers who can close quickly, and close coordination with the court calendar so the closing lands before the auction date. Philadelphia sheriff sales are scheduled through the Court of Common Pleas, and once a date is set, the sheriff's office posts written notice at least 30 days in advance. The earlier you start, the more room the calendar gives you.

Every step is explained on the stop foreclosure help page for Roxborough, which covers working with your lender, a loan modification, a short sale, and selling before the sheriff sale. If speaking with the lender is the best route, he guides you to coordinate with your lender. When the mortgage weighs more than the home can carry, the short sale guidance for Roxborough walks through selling for less than you owe with the lender's approval, and the expired listing help in Roxborough shows how a relaunch gets a home sold after a past listing did not. The full process, from first missed payment to auction, is in the foreclosure and short sale guidance for Philadelphia, and the guide to selling before foreclosure in Philadelphia walks through a pre-sale sale step by step.

If your Roxborough home has a foreclosure case moving and you want to sell before the sheriff sale, you do not have to figure it out alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language plan for selling before the sale date or negotiating with your lender. Every conversation is confidential, and there is no judgment, only solutions.
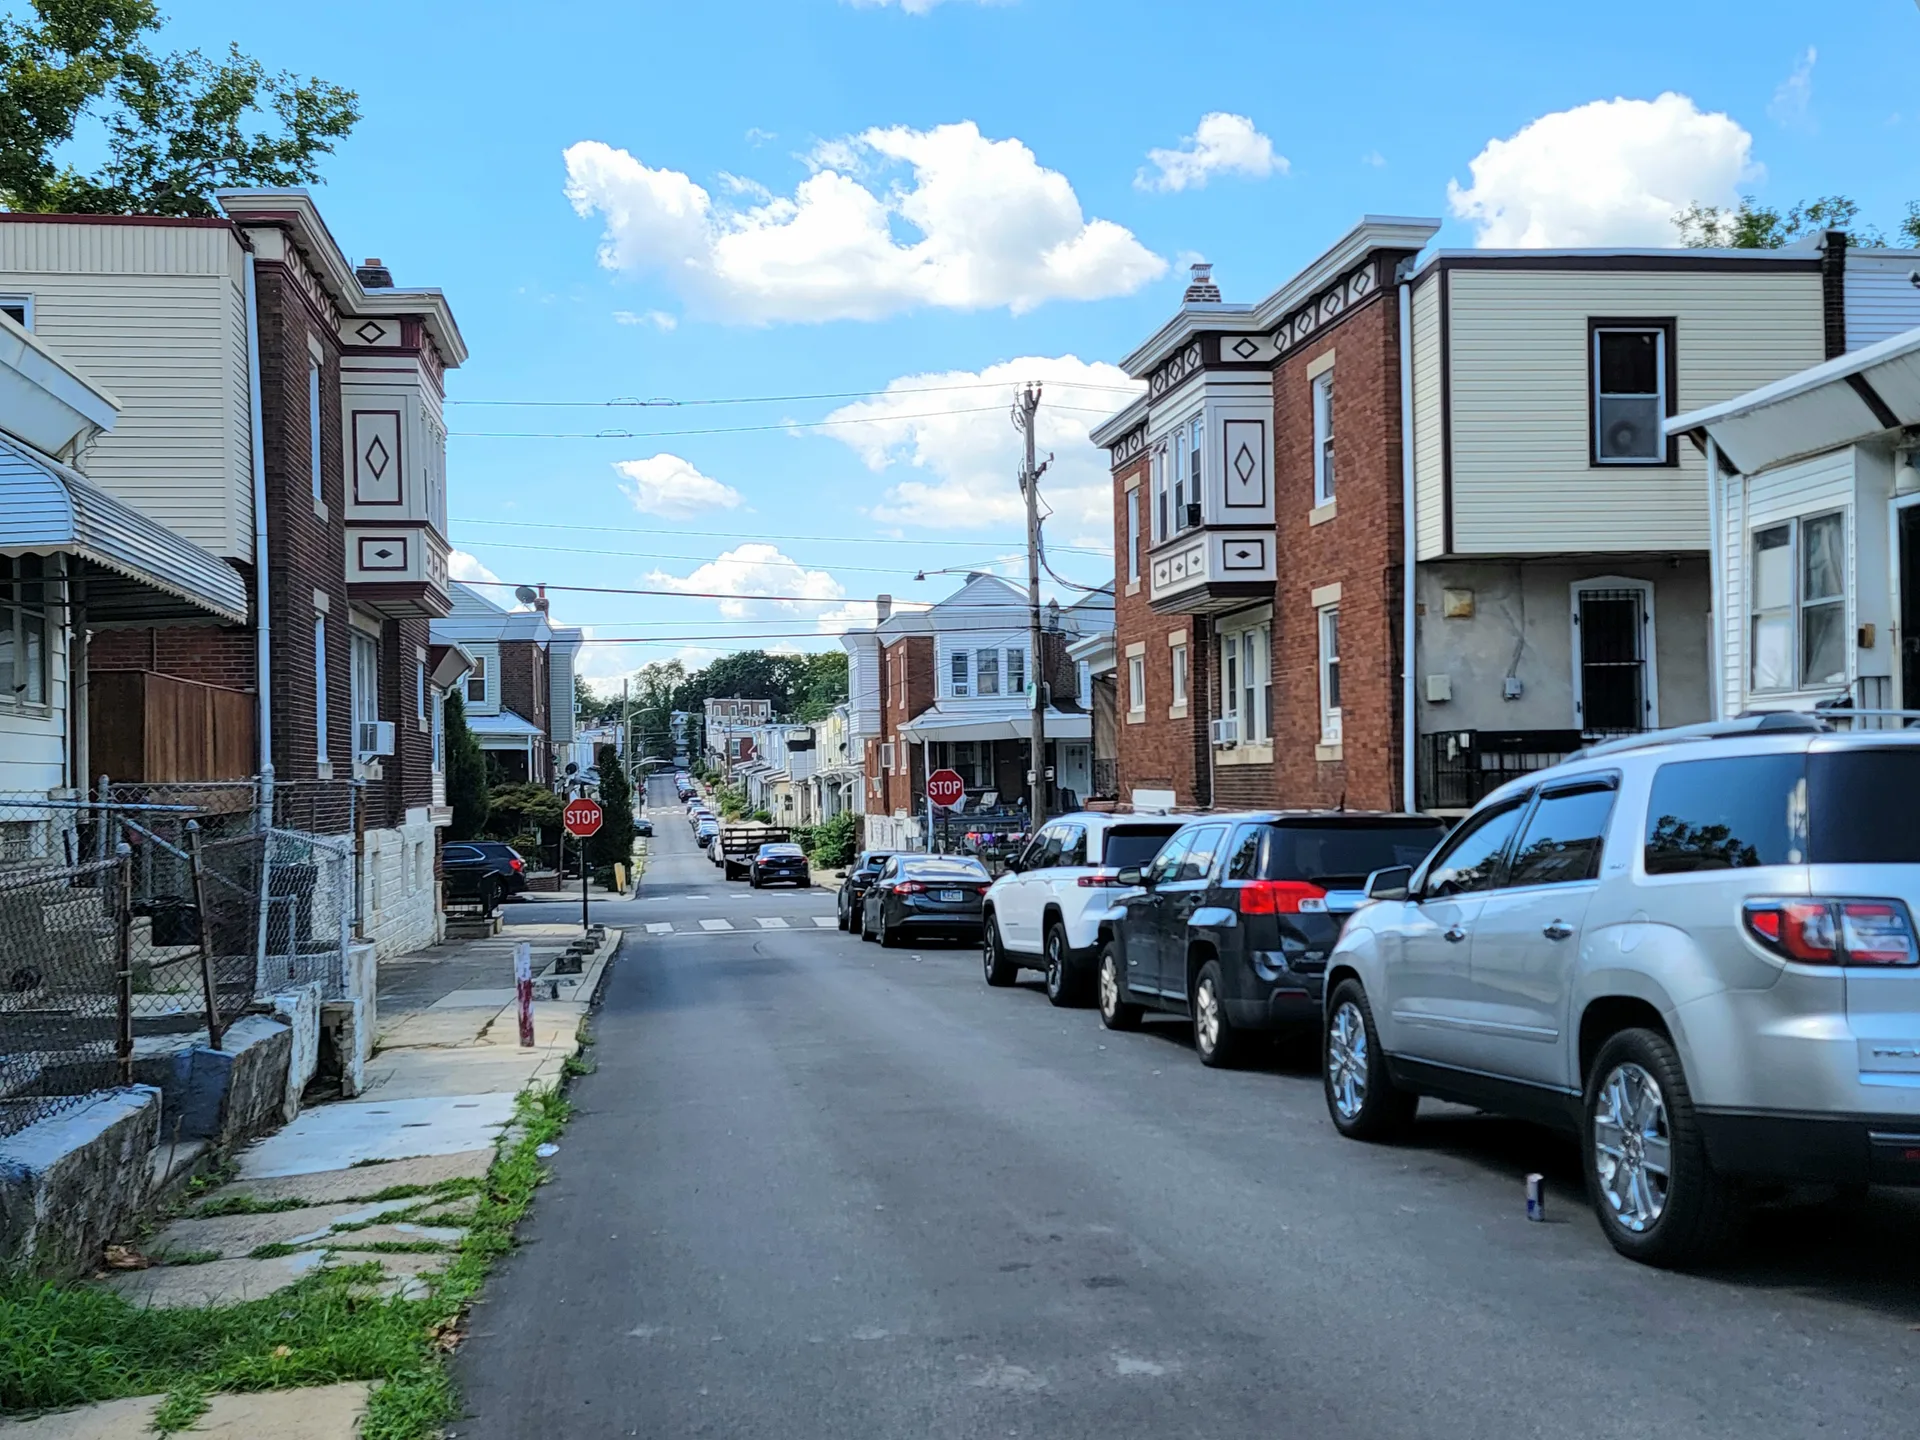
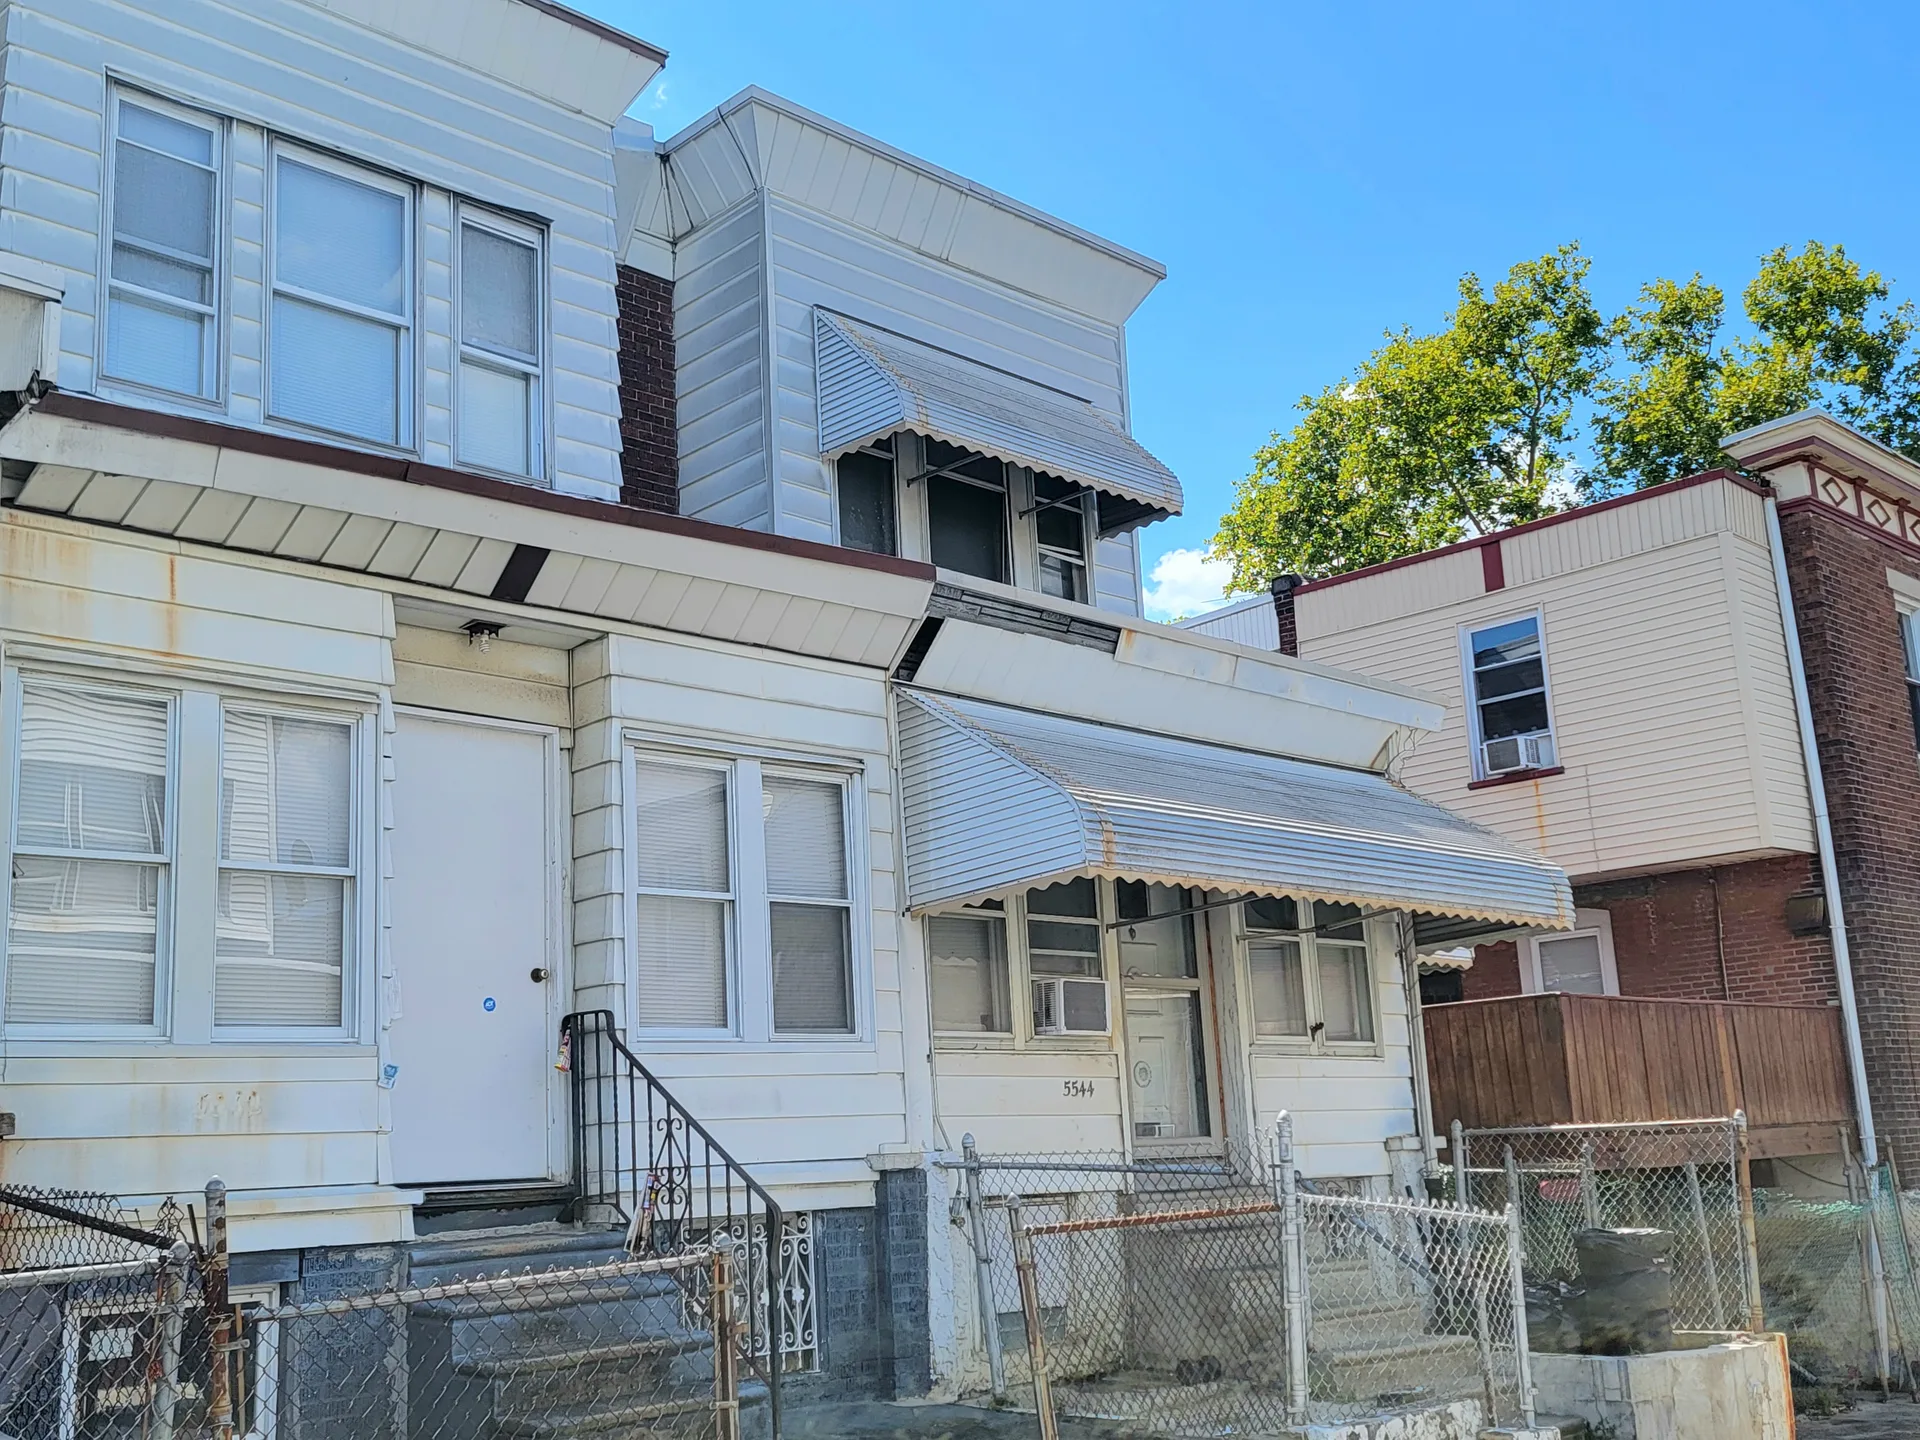
A residential street in Philadelphia lined with brick and siding row homes under a clear blue sky
Stop Foreclosure

Can I Still Do a Short Sale After a Foreclosure Lawsuit Is Filed on My Roxborough Home in Philadelphia?

Yes. In Pennsylvania, you can complete a short sale after a foreclosure lawsuit has been filed, and even after a judgment is entered, as long as the sale closes before the Philadelphia sheriff sale is completed. You remain the owner of your Roxborough home until the auction transfers title, which means the window to sell stays open right up to the sale date.

Roxborough homeowners who have lived on the hilltop above the river valley for decades built their equity the steady way, one payment at a time, in brick rowhomes and twins that the neighborhood holds onto. When a foreclosure complaint arrives in the mail, a common reaction is to assume the house is already gone and a short sale is off the table. That assumption is wrong. The lawsuit changes your timeline, not your ownership, and a short sale remains a practical way to settle the debt and close this chapter on your own terms.

Can you really sell after the foreclosure lawsuit is filed?

Yes. Foreclosure in Pennsylvania is a judicial process, which means the case moves through the courts in stages, and you hold title to your Roxborough home until the sheriff sale is completed. The filing itself does not take your ownership away. A short sale asks the lender to approve a sale for less than the mortgage balance and release the lien, and lenders regularly say yes after a lawsuit has been filed, because a negotiated sale generally costs them less than running the auction.

How close to the sheriff sale is too late?

Your practical deadline is the sheriff sale date itself. There is no separate statutory cutoff: the short sale must actually close before the auction is completed, not merely go under contract. In Philadelphia, the sheriff sale is typically scheduled 30 to 60 days after a judgment is entered, which usually leaves between one and three months from the filing to the sale date. The sheriff's office posts and mails written notice at least 30 days in advance under Pennsylvania Rule of Civil Procedure 3129.2, so when that notice arrives, you can see the deadline in writing.

Will the lender approve a short sale this late in the process?

Very often, yes, and it happens more than people expect. The lender's loss mitigation department can review and approve a short sale after a complaint is filed, and the sheriff sale can be postponed, continued, stayed, or removed from the sale list while the review runs. There is a catch: the lender is not required to pause the calendar. If the sale date stays active while the short sale is reviewed, the auction can move forward on schedule. In Philadelphia, a postponement request must reach the sheriff's office before 3:00 p.m. the day before the auction, so the whole process has to move with the court calendar in mind.

What happens to the foreclosure if the short sale closes?

When the short sale closes, the proceeds pay the mortgage, the lender releases the lien, and the foreclosure case is brought to an end. Because Pennsylvania is a recourse state, the remaining balance is the open question. Andre negotiates the short sale for you and works to try and secure a deficiency waiver so the lender does not come after you for the difference. A waiver is negotiated as part of the deal, not assumed, which is why it needs to be requested and put in writing with the lender's approval.

How do you start a short sale during foreclosure in Roxborough?

A short sale during foreclosure follows the same shape as any other, with a compressed timeline: an honest read on what your home can sell for, a listing aimed at buyers who can close quickly, a complete short sale package to the lender, and close coordination with the court schedule. Because you still own the home, the simpler paths still exist too, catching up on payments or negotiating a loan modification. That is why the first conversation is about your situation and your numbers, not a sales pitch.

Every step is explained on the stop foreclosure help page for Roxborough, which covers working with your lender, a loan modification, a short sale, and selling before the sheriff sale. If speaking with the lender is the best route, he guides you to coordinate with your lender. When the mortgage weighs more than the home can carry, the short sale guidance for Roxborough walks through selling for less than you owe with the lender's approval, and the expired listing help in Roxborough shows how a relaunch gets a home sold after a past listing did not. The full process, from first missed payment to auction, is in the foreclosure and short sale guidance for Philadelphia, and the guide to how long you have before foreclosure in Pennsylvania maps your timeline.

The filing date does not decide how your story ends; you still do. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language read on whether a short sale can still work for your Roxborough home, and what has to happen before the sheriff sale date. Every conversation is confidential, and there is no judgment, only solutions.


A traditional Philadelphia row house with vinyl siding, a brick foundation, and metal window awnings on a sunny day
Stop Foreclosure

What Happens If No One Bids at My Roxborough Home's Sheriff Sale?

If no outside bidder buys your Roxborough home at the Philadelphia sheriff sale, the lender usually takes the property back at the upset price and the home becomes bank-owned. The sale can also be postponed to a later date, but neither outcome protects the equity you have built, which is why selling before the sale date is the move that keeps your options open.

Roxborough homeowners who have lived on the hilltop above the river valley for decades often have real equity in their brick rowhomes and twins. If your home carries a sheriff sale date, you may have wondered what happens when the auction arrives and nobody bids. It is a fair question, and the answer matters because it decides who ends up with your home and what happens to the value you built.

What is the upset price at a Philadelphia sheriff sale?

The upset price is the minimum amount the foreclosing lender will accept for the property. Philadelphia sheriff sales now run as online auctions, and the lender's attorney submits the upset price to the auction platform before the sale starts, with the sheriff's costs added to the bid. It is the floor under the auction, and it tells you the lowest price the lender is willing to take.

Does the lender usually bid at the sheriff sale?

In most cases, yes. Lenders bid the upset price so the home does not sell for less than they are willing to accept. When the lender is the winning bidder, the home becomes bank-owned real estate and the foreclosure runs its course. That is the outcome where the equity you built in a Roxborough row home is lost, which is why a no-bid result is not a win for you.

Can the sheriff sale be postponed if no one bids?

Yes. Under Pennsylvania Rule of Civil Procedure 3129.3, a sheriff sale with no bids may be stayed, continued, postponed, or adjourned to a later date, typically within 130 days, with new notice to everyone involved. The Philadelphia Land Bank also places priority bids on certain properties on the sale list. A postponement buys time, but the underlying foreclosure is still moving, and the clock restarts.

What happens to my equity if the lender takes the home?

If the lender takes the property at the upset price, any equity above what you owe is gone, and Pennsylvania is a recourse state, which means a deficiency judgment remains possible after the sale. That is the double hit homeowners want to avoid: losing the home and still owing on the mortgage. Selling before the sheriff sale avoids both.

Can I still sell my Roxborough home before the sale date?

Yes. You own your home until the sheriff sale is completed, so you can sell at any point before the auction date. A sale at or near market value pays off the mortgage, protects the equity you have built, and stops the foreclosure process. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can do the same, and Andre negotiates for you and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

Every step is explained on the stop foreclosure help page for Roxborough, which covers working with your lender, a loan modification, a short sale, and selling before the sheriff sale. If speaking with the lender is the best route, he guides you to coordinate with your lender. When the mortgage weighs more than the home can carry, the short sale guidance for Roxborough walks through selling for less than you owe with the lender's approval, and the expired listing help in Roxborough shows how a relaunch gets a home sold after a past listing did not. The full process, from first missed payment to auction, is in the foreclosure and short sale guidance for Philadelphia, and the guide to how long you have before foreclosure in Pennsylvania maps your timeline.

If your Roxborough home has a sheriff sale date approaching, you do not have to wait for the auction to decide your future. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language plan for selling before the sale date or negotiating with your lender. Every conversation is confidential, and there is no judgment, only solutions.


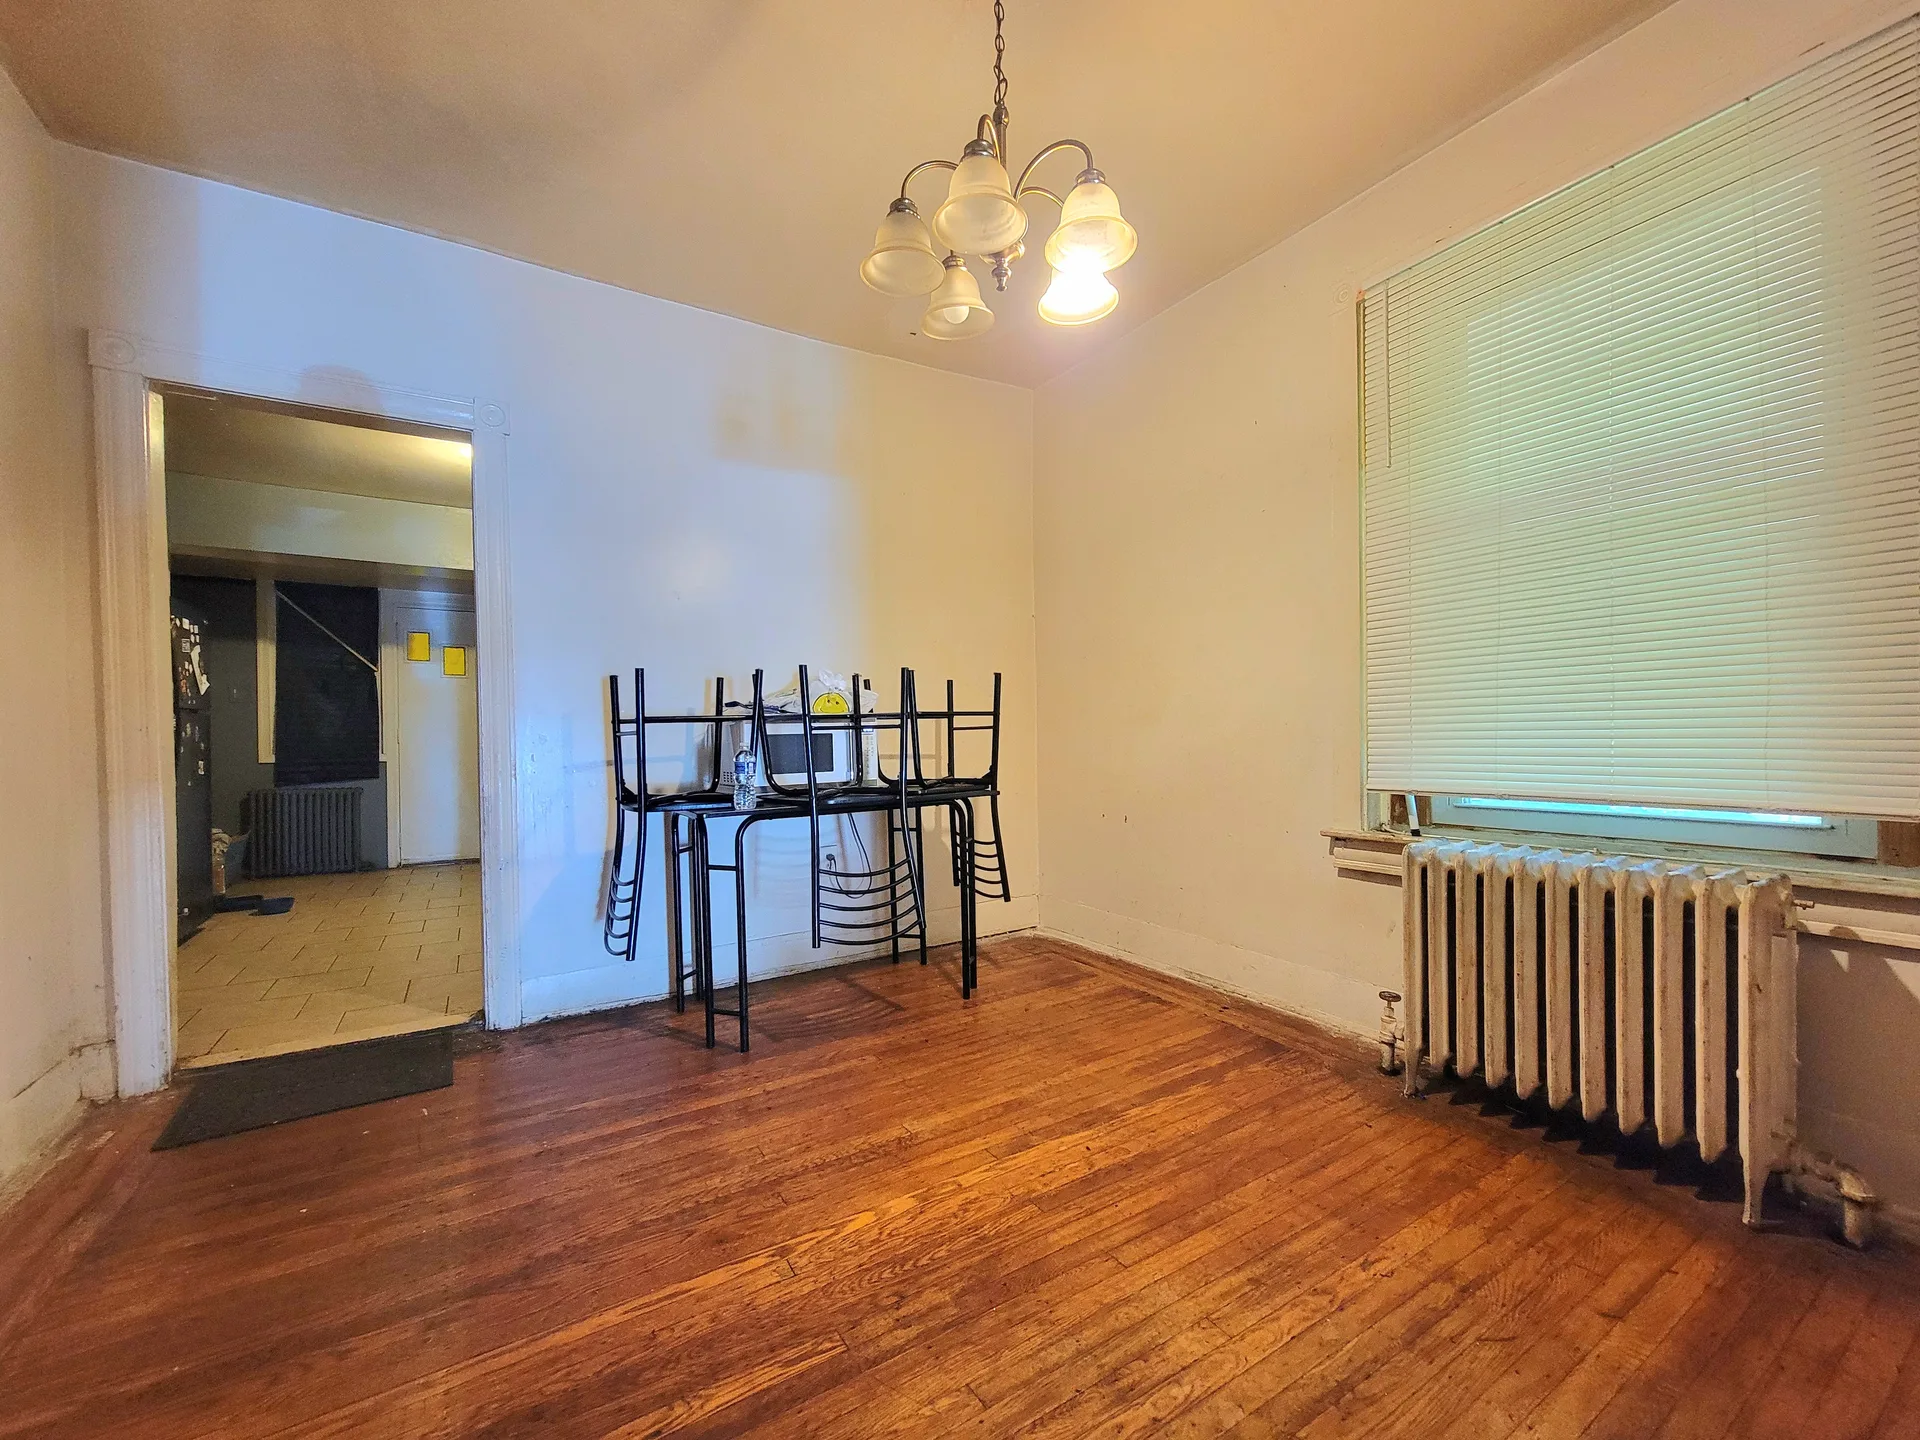
A dining room in a Philadelphia row home with hardwood floors, white walls, and a cast iron radiator in natural daylight
Stop Foreclosure

What Happens at a Philadelphia Foreclosure Conciliation Conference?

The Philadelphia foreclosure conciliation conference is a court-scheduled meeting between you, a free housing counselor, and your lender's representative, held before any foreclosure judgment can be entered. For an owner-occupied home in Philadelphia, attending is mandatory, and the purpose is to work out an alternative to foreclosure, such as a loan modification or a repayment plan, instead of moving toward a sheriff sale.

If you live in Roxborough and you have fallen behind on your mortgage, Philadelphia's court process may not look like what you expect. After a foreclosure complaint is filed, an owner-occupied case is steered toward a conciliation conference rather than straight to judgment or sheriff sale. That is the Mortgage Foreclosure Diversion Program of the Court of Common Pleas of Philadelphia County, and attending is mandatory to keep its protections. The pause it creates is real leverage, and using that time well matters.

What is the conciliation conference?

Inside the conference, you sit at a table with your housing counselor, a facilitator, and the lender's representative. Everyone reviews your finances and tries to agree on a way to keep the case out of judgment: a loan modification that rewrites the payment to fit your income, a repayment plan that catches up the arrears, or another arrangement the lender can approve. If an agreement is reached, the documents are prepared and the complaint is withdrawn. In practical terms, it is a court-scheduled negotiation with the party who holds your mortgage, and it cannot simply be ignored.

When and where does the conference take place?

The first conference is usually scheduled about two months after the foreclosure complaint is filed, and the court notice states your exact date and time. Conferences are held in Room 676 of Philadelphia City Hall, always on a Thursday, in a 9:00 a.m. or 1:00 p.m. session. For a Roxborough homeowner, that means crossing the river into Center City for a morning or early afternoon meeting, and it is worth making the trip.

What should I do before the conference?

Call the Save Your Home Philly Hotline at 215-334-4663 as soon as you receive the notice. The hotline, run by the City of Philadelphia with Philadelphia Legal Assistance, connects you with a free housing counselor who reviews your finances and prepares a written proposal to present at the conference, typically a loan modification built around your income and expenses. Bring recent pay stubs, bank statements, tax returns, and a list of your monthly bills.

Can the conference stop the sheriff sale?

Yes, when an agreement is reached. If you and the lender's representative agree on a loan modification, a repayment plan, or another arrangement, the documents are prepared and the complaint is withdrawn, ending the march toward the sheriff sale. If no agreement is reached, the case continues toward judgment and eventually a sheriff sale date. That is why preparation matters: the conference is your strongest structured chance to reset the mortgage before the auction is scheduled.

What happens if I miss the conference?

Philadelphia's diversion program requires the homeowner to attend in person. If you do not appear, your case moves forward without the program's protections, typically toward judgment and a sheriff sale. Treat the conference date like a hearing, because in practical terms it is one.

Can I still sell my Roxborough home instead?

Yes, and the conference does not take selling off the table. You own your home until the sheriff sale is completed, and a sale at market value can pay off the mortgage, protect the equity you have built in a Roxborough row home or twin, and put the case behind you on your terms. If you owe more than the home can carry, a short sale with the lender's approval can do the same. Andre negotiates the short sale for you and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

Every step is explained on the stop foreclosure help page for Roxborough, which covers working with your lender, a loan modification, a short sale, and selling before the sheriff sale. If speaking with the lender is the best route, he guides you to coordinate with your lender. When the mortgage weighs more than the home can carry, the short sale guidance for Roxborough walks through selling for less than you owe with the lender's approval, and the expired listing help in Roxborough shows how a relaunch gets a home sold after a past listing did not. The full process, from first missed payment to auction, is in the foreclosure and short sale guidance for Philadelphia, and the guide to how long you have before foreclosure in Pennsylvania maps your timeline.

If a conciliation conference or a foreclosure complaint is on your calendar in Roxborough, you do not have to face it alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language plan for negotiating with your lender or selling before the sheriff sale. Every conversation is confidential, and there is no judgment, only solutions.

Your Roxborough home
is worth protecting.

Let's talk about your options, on your timeline.

Want to know what your home is worth? Get a real valuation of your home's value.

Licensed. Local. Legit.

Pennsylvania License RS349905 · New Jersey License 1969348
HomeSmart Realty Advisors

Experience. Strategy. Results.

267-977-0304

Need more room to move? Read the full foreclosure and short sale guidance for Philadelphia, see expired listing help in Roxborough if your home has already been through a listing that didn't sell, or contact Andre directly.