Stop foreclosure help in West Mount Airy, Philadelphia with Andre Richardson, Realtor — the go-to agent for foreclosure help in West Mount Airy
Stop Foreclosure

Foreclosure Help
in West Mount Airy

You have more options than you think.

West Mount Airy is one of the city's most sought-after leafy communities, its winding, tree-lined streets lined with stone twins that have drawn generations of homeowners who value space, green, and community. For most West Mount Airy homeowners, the house is the largest asset they own, with equity that the neighborhood's lasting desirability has kept strong. I'm Andre Richardson, and for 26 years I've been involved with Philadelphia real estate. Facing foreclosure doesn't mean your story is over. It means it's time to look at your options, and the earlier you do, the more choices you have.

26 Years
Real Estate Experience
5.0
Rating from 27 Reviews
AI
Powered Marketing
PA & NJ
Licensed
01
Why It Matters

Why Acting Early Matters
in West Mount Airy

One of Philadelphia's most sought-after leafy communities, West Mount Airy is known for winding, tree-lined streets and handsome stone twins. Homeowners here chose the neighborhood for its green, its space, and its community, and over the years that desirability has protected property values. For most West Mount Airy homeowners, the house is the largest asset they own. When a mortgage becomes hard to keep up with, that equity is exactly what makes acting early matter.

  • The earlier you act, the more options you have: a repayment plan, forbearance, a loan modification, a short sale, or a sale at full market value
  • West Mount Airy's reputation as a sought-after community keeps a steady stream of qualified buyers, which works in your favor when you need to sell on a timeline
  • Time protects equity: every month spent waiting narrows the gap between what you owe and what your home is worth
  • Solutions like a loan modification are far easier to secure before the process moves deep into the courts

Foreclosure in Pennsylvania is a judicial process, which means it moves in stages and there is a path forward at every stage. The mistake homeowners make is waiting to find it. The homeowners who call early keep control of the outcome, and in West Mount Airy, where one of the city's strongest neighborhoods protects values, early action is how that equity gets protected.


02
Your Options

Options Beyond Foreclosure,
with Someone on Your Side

You have more options than you think. Each path below is a real, workable route, and every one of them goes better with Andre Richardson leading the way. He listens to your situation first, then builds the plan around your lender and your timeline.

Working with your lender

Before anything else, there may be room to work directly with your mortgage servicer: a repayment plan to catch up on missed payments, a forbearance that pauses payments for a set period, or a reinstatement agreement. Andre reviews your specific situation, and if speaking with your lender is the best route, he guides you to coordinate with your lender.

A loan modification

A loan modification rewrites the terms of your mortgage so the payment fits your current income, through a lower rate, a longer term, or added arrears. Modifications are far more attainable early in the process, and Andre will point you to talk with your lender.

A professionally guided short sale

If you owe more than the home can sell for, a short sale lets you sell with the lender's approval and walk away from the threat of foreclosure. Andre manages the entire negotiation for you, from the loss mitigation department to the paperwork, and works to try and secure a deficiency waiver so the lender does not come after you for the difference.

Selling before foreclosure

If your West Mount Airy home holds equity, selling on the open market before the sheriff sale is often the strongest path. You capture the value your home has built, pay off the mortgage, protect your credit, and close the chapter on your terms, with Andre's aggressive AI-infused marketing working towards getting your home sold.

These paths are explained step by step in the full foreclosure and short sale guidance for Philadelphia, covering timelines, credit impacts, and lender negotiations. If the mortgage weighs more than the home can carry, the short sale guidance in West Mount Airy page walks through selling for less than you owe with the lender's approval. And if your home has already been through a listing that did not sell, the expired listing help in West Mount Airy page shows how a relaunch gets it sold. You do not have to choose a path alone.


03
The Agent

Why Sellers Trust Andre

By the time West Mount Airy homeowners facing foreclosure find me, many have been carrying the weight of the situation alone for months, and some have watched a previous listing fail. I bring 26 years of Philadelphia and South Jersey experience, active PA and New Jersey licenses, and a targeted marketing plan that gets homes sold. Every conversation is confidential, and there is no judgment, only solutions.

“Andre was very professional and knowledgeable, a definite credit to the profession. I would not hesitate to refer him to any of my friends or family for his real estate services. Andre did not hesitate to go above and beyond to make things happen. Job well done for me thank you Andre!”

— Stella Thompson, 5-star review

See how the sell my house process works or read the client reviews from sellers who started right where you are.


04
Answers

Questions West Mount Airy Homeowners
Facing Foreclosure Ask

Can I sell my West Mount Airy home after receiving a foreclosure notice?

Yes. You can sell at any point before the sheriff sale, and in West Mount Airy, where stone twins on sought-after leaf-lined streets hold real equity, selling before foreclosure is often the strongest path. A sale at or near market value lets you pay off the mortgage, keep what equity remains, and protect your credit. The key is starting now, because the timeline moves faster than most homeowners expect.

How long does a Pennsylvania foreclosure give me to act?

The foreclosure process in Pennsylvania typically runs six to twelve months from the first missed payment to the sheriff sale, and federal law requires a 120-day waiting period before a lender can even begin formal proceedings. Philadelphia's Mortgage Foreclosure Diversion Program, which requires a conciliation conference, can extend that window. In a sought-after neighborhood like West Mount Airy, that window is usually enough to sell well if you act immediately.

Are West Mount Airy stone twins still in demand with buyers?

Yes. Stone twins on winding, tree-lined streets in West Mount Airy remain among the most desirable homes in the city, and buyers actively seek them out. That demand is leverage you can use: it means a well-marketed pre-foreclosure sale can reasonably be expected to attract solid offers in a short window. The key is honest pricing and aggressive marketing from day one.

Will a short sale protect me from the lender coming after the difference?

Pennsylvania is a recourse state, which means a deficiency judgment is possible after a foreclosure or a short sale unless it is waived. That is why the short sale agreement should include a deficiency waiver, a written provision that the lender will not pursue you for the remaining balance. Andre negotiates for that protection in every short sale he manages. A short sale also impacts credit far less than a completed foreclosure, and you can qualify for a new mortgage years sooner.

What happens if I do nothing?

If nothing changes, the process continues through the courts to a sheriff sale, where the property is sold at auction either to a private buyer or to the lender. You lose the equity in the home, your credit takes its hardest hit, and a deficiency judgment remains possible in Pennsylvania. That outcome is almost always avoidable, and the homeowners who call early keep the most control over how their story ends.

05
From the Blog

West Mount Airy Foreclosure
Advice

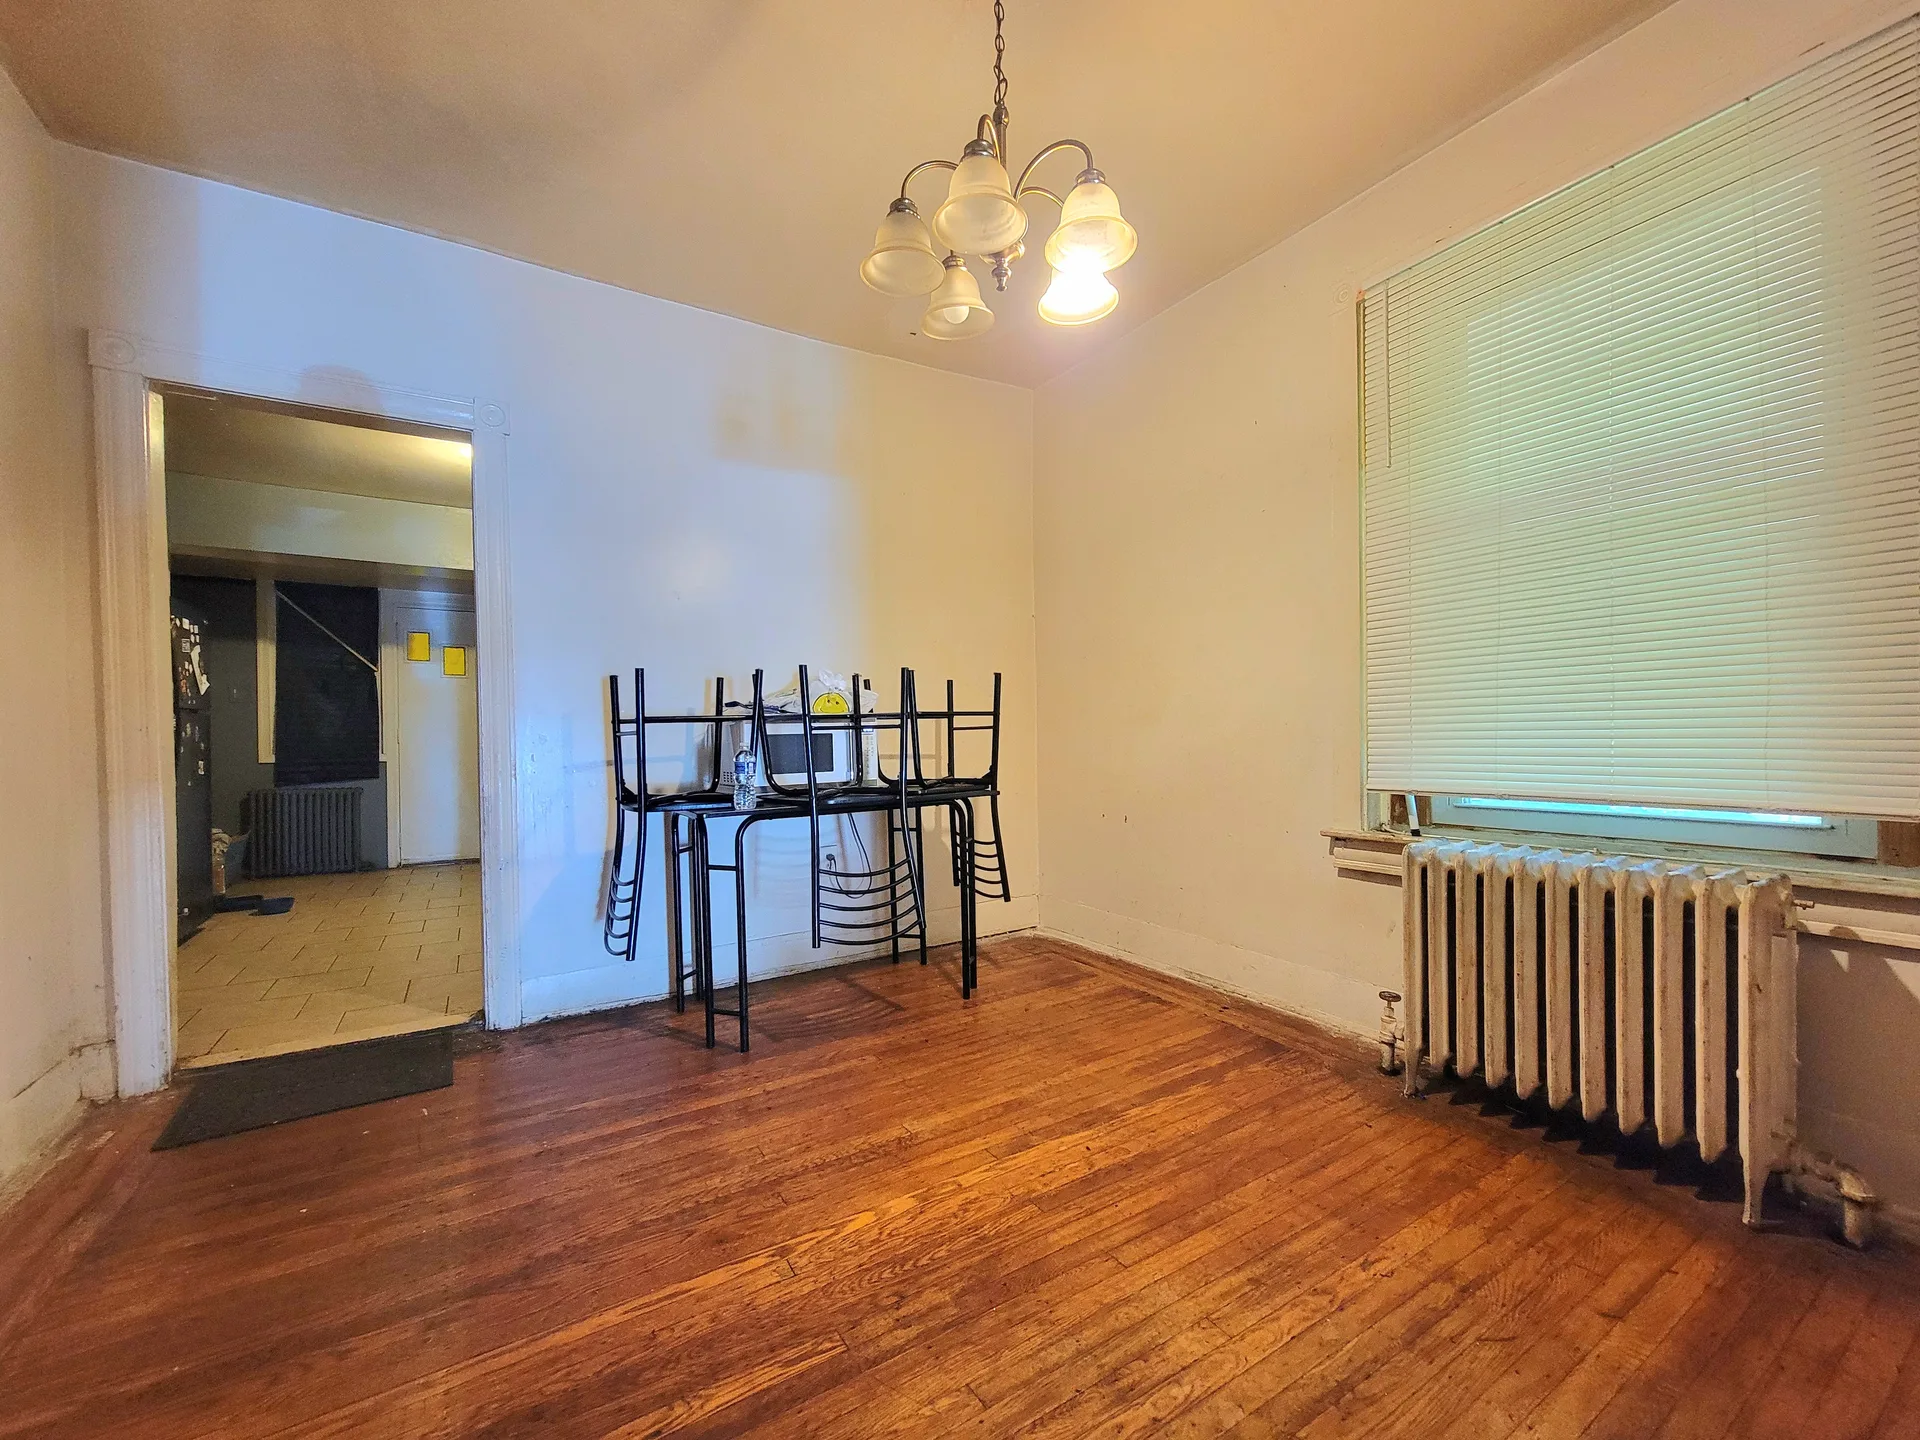
A bright dining room with hardwood floors in a Philadelphia home, the kind of West Mount Airy home a homeowner works to keep when a mortgage payment increases
Stop Foreclosure

Why Did My Mortgage Payment Suddenly Increase in West Mount Airy, Philadelphia?

Your payment most likely went up because of an escrow shortage: your mortgage servicer's annual escrow analysis found that rising property taxes or homeowners insurance will cost more than what you have been paying in, so it raised your monthly payment to cover the difference. The increase itself does not start a Philadelphia foreclosure. Falling behind because the new payment no longer fits your budget is what moves a West Mount Airy home toward the sheriff sale process, and there are steps you can take at every stage.

If you live in West Mount Airy, Philadelphia, PA and your mortgage payment just jumped, you are not imagining it, and you are not alone. "My mortgage payments suddenly increased, what can I do?" is one of the most common calls to Philadelphia's Save Your Home Philly hotline, the city's foreclosure-prevention program staffed by lawyers and paralegals. Whether your home is a Wissahickon schist stone twin on a winding, tree-lined street or a house closer to Germantown Avenue, a payment increase does not happen without a reason, and most of the reasons have a fix.

What are the most common reasons a mortgage payment goes up?

An escrow shortage is the most common reason a monthly payment changes, even on a fixed-rate loan, according to the Consumer Financial Protection Bureau. The other frequent causes are an adjustable-rate mortgage resetting to a higher rate, force-placed insurance that your servicer buys when your own policy lapses, and a forbearance period ending with the paused payments due. Each cause shows up on your statement, and each one is handled differently.

Why did my escrow payment jump?

Your escrow account collects a slice of your payment to pay your property taxes and homeowners insurance when they come due. When Philadelphia reassesses your home's value and your tax bill rises, or your insurance premium goes up, the servicer's annual escrow analysis catches the shortfall and raises your payment to cover it. Under federal rules, the servicer sends an annual escrow statement within 30 days after your escrow computation year ends, and a shortage is typically spread over 12 months. If you disagree with the tax side, a free First Level Review with the city's Office of Property Assessment is open to you, and so is a formal appeal to the Board of Revision of Taxes.

Can a payment increase really push my West Mount Airy home into foreclosure?

Only if the higher payment means you fall behind. Pennsylvania foreclosures are judicial, which means the process runs through the Court of Common Pleas and, if nothing changes, ends at a Philadelphia sheriff sale. Federal rules require a 120-day waiting period before a lender can begin formal proceedings, and Philadelphia's Mortgage Foreclosure Diversion Program adds a conciliation conference that can buy time. That window is real, but it is not unlimited, and the earlier you act, the more options you keep.

What should I do if I can't afford the higher payment?

Start by reading the payment change notice and your statement breakdown so you know exactly what increased. Then contact your servicer and ask why, and put any dispute in writing. If the increase came from an escrow shortage, appeal the Philadelphia assessment and shop for a lower homeowners insurance premium. If it came from force-placed insurance, get your own policy and send proof to the servicer to cancel it. If it came from a forbearance that ended, call the servicer before the next payment is due to arrange a repayment plan or a loan modification. If the servicer will not fix an error, you can file a complaint with the Consumer Financial Protection Bureau, and the Save Your Home Philly hotline is a free place to start.

Can selling my West Mount Airy home solve this?

For many West Mount Airy homeowners, yes. If the higher payment no longer fits, selling before the sheriff sale can pay off the mortgage, protect the equity built into the home, and end the case on your terms. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can do the same, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.

The full process is laid out on the stop foreclosure help page for West Mount Airy, covering working with your lender, a loan modification, a pre-foreclosure sale, and a short sale step by step. If the mortgage weighs more than the home can carry, the short sale guidance for West Mount Airy walks through selling for less than you owe with the lender's approval. If your home already went through a listing that did not sell, the expired listing help for West Mount Airy shows how a relaunch gets it sold. The complete timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the guide to what happens if you can't catch up on your mortgage in Pennsylvania shows the road ahead when payments are no longer affordable.

If your West Mount Airy mortgage payment just increased and you are not sure you can carry it, you do not have to sort it out alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language read on your options before the sheriff sale. Every conversation is confidential, and there is no judgment, only solutions.
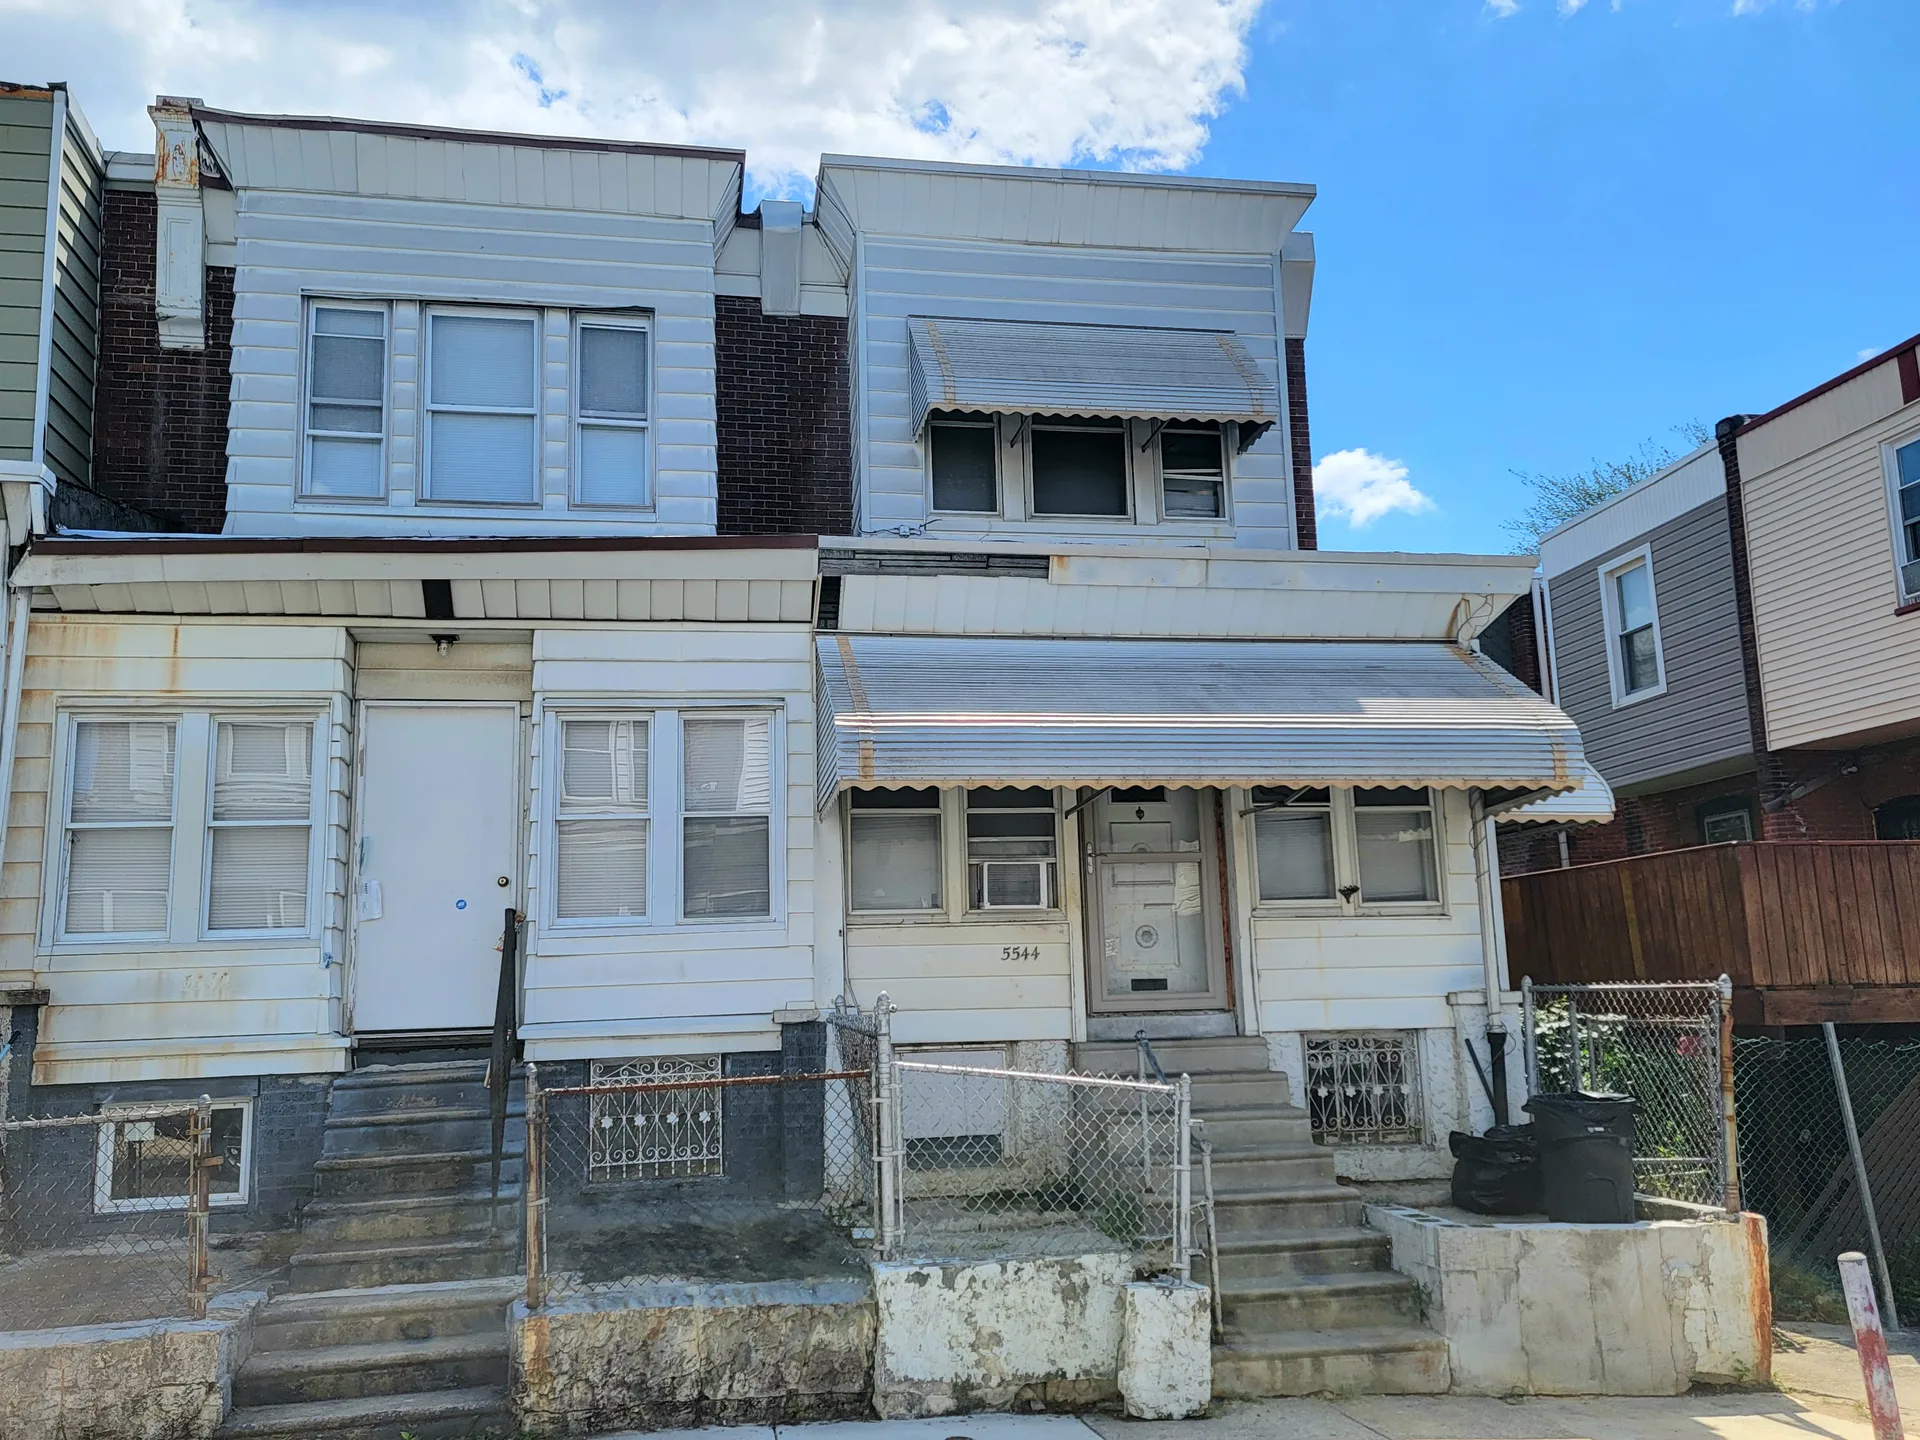
Two attached Philadelphia homes with stone foundations in bright daylight, the kind of property a West Mount Airy homeowner still legally owns while a foreclosure case is pending
Stop Foreclosure

Who Owns My West Mount Airy Home While It's in Foreclosure in Philadelphia?

You do. If your West Mount Airy home is in a Philadelphia foreclosure case, you remain the legal owner until the sheriff sale is completed and the sheriff's deed is delivered to the winning bidder. The bank holds the mortgage as a lien against your property, not the deed to your house, and it does not become the owner the day you miss a payment. That fact, understood clearly, is the foundation for everything you can still do.

If you live in West Mount Airy, Philadelphia, PA and foreclosure papers have arrived, the question underneath the fear is often this one: is my house already the bank's? The answer is no. Pennsylvania foreclosure is a judicial process, which means it runs through the Court of Common Pleas and it ends, if nothing changes, at a Philadelphia sheriff sale. Between the first missed payment and that auction, the home is still yours. West Mount Airy's stone twins on winding, tree-lined streets have carried generations of owners with real equity, and you still hold that deed while the case moves.

Do I still own my home after I miss a mortgage payment?

Yes. Missing a payment does not move title. Your mortgage is a contract secured by a lien, and a lien is not ownership. The lender's path to the house is through court: a lawsuit, a judgment, and eventually the sheriff sale. Until that sale is complete, you hold the deed, you can live in the home, and you can keep making decisions about it, including selling it.

When does the bank actually become the owner in a Philadelphia foreclosure?

Only at the sheriff sale. The Sheriff's Office auctions the property to the highest bidder, and the lender is allowed to bid the amount you owe. Ownership changes hands when the sheriff executes and delivers the sheriff's deed to the winning bidder after the sale is complete. If someone files a petition to set the sale aside, the transfer is held up while the court resolves it. Either way, nothing transfers at the lawsuit and nothing transfers at the judgment. The deed moving is the moment.

Can the bank come onto my property or take the keys before the sheriff sale?

Generally no. Because ownership begins with the sale, not with the lawsuit, the lender cannot evict you or simply take possession while the case is pending. If a home sits vacant, a lender may take steps to secure and protect it, but for an occupied West Mount Airy home, possession changes hands only through the court process after the deed is delivered. That means no one shows up with a lockbox and a moving truck before the sale, and it means you have room to act.

Can I sell my West Mount Airy home while I am still the legal owner?

Yes, and this is where being the legal owner turns into your advantage. You can list and close before the sheriff sale as long as the proceeds cover the mortgage payoff, taxes, liens, and closing costs. West Mount Airy's leafy streets and sought-after stone twins keep a steady stream of qualified buyers, which works in your favor when time is short. A pre-foreclosure sale at market value pays off the mortgage, protects the equity built into the home, and ends the case before the auction. If the balance is more than the home can carry, a short sale with the lender's approval is often the cleanest exit, and Andre manages the negotiation and works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.

What happens if the lender wins the bid at my sheriff sale?

The lender can become the buyer. By bidding the amount you owe, the bank often ends up as the winning bidder, and afterward the process works the same as with any buyer: a notice to vacate, an ejectment action if you remain, a writ of possession, and finally the sheriff scheduling the move-out. That outcome is exactly what the options above are designed to prevent, and every one of them happens while you still hold the deed.

The full process is laid out on the stop foreclosure help page for West Mount Airy, covering working with your lender, a loan modification, a pre-foreclosure sale, and a short sale step by step. If the mortgage weighs more than the home can carry, the short sale guidance for West Mount Airy walks through selling for less than you owe with the lender's approval. If your home already went through a listing that did not sell, the expired listing help for West Mount Airy shows how a relaunch gets it sold. The timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the step-by-step guide to selling your home before foreclosure in Philadelphia and South Jersey shows the practical side of a pre-foreclosure sale.

If you are in a Philadelphia foreclosure case and you want to know exactly where you stand, you do not have to sort it out alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language read on your options while you still hold the deed. Every conversation is confidential, and there is no judgment, only solutions.

A furnished living room in a Philadelphia home, filled with the personal belongings a West Mount Airy homeowner works to protect
Stop Foreclosure

What Happens to My Belongings If My West Mount Airy Home Sells at a Philadelphia Sheriff Sale?

Your belongings do not transfer with the house. Once the Philadelphia sheriff delivers the deed to the buyer, the new owner owns the property, and anything you leave inside can be treated as abandoned and disposed of. The house sale changes who owns the home, not who owns your furniture, your photos, or your keepsakes, but those items are only safe if you move them, and the earlier you move them, the safer they are.

If you live in West Mount Airy, Philadelphia, PA and a sheriff sale date is on the calendar, this is the practical question behind the scary one. Foreclosure in Pennsylvania runs through the Court of Common Pleas, and in Philadelphia it ends at the Sheriff's Office, where the property is auctioned. West Mount Airy homes, the stone twins on winding, tree-lined streets that families here have held for generations, carry real equity, and that equity is a reason to act well before the sale date arrives. But if the sale does go through, knowing exactly what happens to your belongings is how you protect them.

How long do I have to move my belongings out after a sheriff sale?

Once the deed changes hands, you no longer own the home, and the new owner has a legal path to possession. The Philadelphia Sheriff's Office process works like this: the new owner writes you a letter giving 30 days to vacate. If you are still there after that, the owner files a Complaint in Ejectment in court. You have 20 days from service to respond. If the owner wins the case, the court issues a writ of possession with a 21-day notice to vacate, and after that the sheriff schedules the physical eviction. An uncontested case often stretches several months, but the clock is set by the new owner, not by you. The safe time to remove your belongings is before the sale or as early as possible in that process, not at the end of it.

Can the new owner throw my belongings away?

If they are left in the home, yes. Pennsylvania law gives the buyer of a property certified vacant and abandoned the right to remove and dispose of personal property left behind, but first the buyer must send you written notice of the intent to remove it, tell you where the belongings can be retrieved, and give you a 10-day window before retrieval starts to cost you. On properties that are not certified, belongings left behind can still be treated as abandoned. The practical rule is the same either way: do not leave the things you cannot afford to lose.

What should I take first if the sale is close?

Start with what cannot be replaced: identification, birth certificates, passports, marriage and children's records, wills, tax returns, bank statements, medications, family photos, and heirlooms. Then move furniture, appliances, clothing, and everything else you want to keep, in stages if that is easier. A storage unit, a relative's basement, or a few careful trips can clear a home faster than it feels. You do not have to do it in one day, but every day you wait, the list of what could be lost grows.

How does selling before the sheriff sale protect your belongings?

This is where acting early changes everything. If you sell your West Mount Airy home before the sheriff sale, you control the move: your belongings travel with you on your schedule, and you close the chapter on your terms instead of on the new owner's. A pre-foreclosure sale at market value can pay off the mortgage, protect the equity built into the home, and end the case before the sale date. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can do the same, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.

The full process is laid out on the stop foreclosure help page for West Mount Airy, covering working with your lender, a loan modification, a pre-foreclosure sale, and a short sale step by step. If the mortgage weighs more than the home can carry, the short sale guidance for West Mount Airy walks through selling for less than you owe with the lender's approval. If your home already went through a listing that did not sell, the expired listing help for West Mount Airy shows how a relaunch gets it sold. The complete timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia.

If you are facing a sheriff sale date in West Mount Airy, you do not have to sort out your options alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language read on your options before the sale. Every conversation is confidential, and there is no judgment, only solutions.

A sunny Philadelphia residential street lined with attached homes, the kind of neighborhood West Mount Airy homeowners are fighting to protect
Stop Foreclosure

Can Filing for Bankruptcy Stop a Foreclosure in West Mount Airy, Philadelphia?

Yes. Filing for bankruptcy triggers the automatic stay, a federal protection that immediately halts foreclosure proceedings, including a scheduled sheriff sale in Philadelphia. The pause is real, but it lasts only as long as the bankruptcy case itself, which is why the choice between Chapter 7 and Chapter 13 matters so much for a West Mount Airy homeowner.

If you live in West Mount Airy and foreclosure papers have arrived, or a sheriff sale date is on the calendar, you have probably asked whether bankruptcy is the answer. It is a real option, and for many homeowners it is the right one. It is also a tool with limits, and knowing exactly how it works matters because Philadelphia's foreclosure path runs through the Court of Common Pleas and ends at a sheriff sale that can be postponed, but is very hard to undo once it happens.

What does the automatic stay actually do?

The moment a bankruptcy petition is filed, the automatic stay goes into effect. It is a federal order under 11 U.S.C. Section 362 that stops foreclosure proceedings, sheriff sales, collection calls, garnishments, and lawsuits against you. In Philadelphia, that means the foreclosure case pauses and the Sheriff's Office will not move forward with a scheduled sale while the stay is in place.

Can bankruptcy stop a sheriff sale that is already scheduled?

Yes. Filing even the day before, or the day of, a scheduled sheriff sale triggers the automatic stay, and the sale is canceled or postponed. There is one hard limit: if the sale has already happened and the deed has passed to the winning bidder, a later filing generally cannot undo it. That is why the timing of the decision matters so much.

How is Chapter 7 different from Chapter 13?

Chapter 7 pauses the foreclosure temporarily. The stay typically lasts three to four months, until the case closes or the lender gets permission to move forward, and Chapter 7 does not catch up your missed payments. If the arrears are not paid, the foreclosure resumes.

Chapter 13 is the chapter that can stop a foreclosure for the long term. The automatic stay lasts through the repayment plan, usually three to five years, and your missed payments are folded into the plan while you keep making current mortgage payments. For a West Mount Airy homeowner who wants to keep the house, Chapter 13 is the chapter that makes that possible.

How long does the protection last?

The stay lasts for the life of the case: a few months in a Chapter 7, three to five years in a Chapter 13. A lender can ask the court to lift the stay, and repeat filings get less protection. If a prior bankruptcy was dismissed within the past year, the stay lasts only 30 days. If two or more cases were dismissed in the prior year, no automatic stay goes into effect at all. Bankruptcy is not a card you can play repeatedly.

What should West Mount Airy homeowners do before filing?

Talk to a bankruptcy attorney first. Bankruptcy is a legal decision with long credit consequences, and your mortgage balance, your equity, and your income all shape whether it is the right move. A completed Chapter 7 stays on your credit report for ten years and a Chapter 13 for seven years, so it is not a step to take on your own.

What are the alternatives to bankruptcy?

For many West Mount Airy homeowners, a sale is a stronger path than bankruptcy. A pre-foreclosure sale at market value can pay off the mortgage, protect the equity built into the home, and end the case before the sheriff sale. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can do the same, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.

The full process is laid out on the stop foreclosure help page for West Mount Airy, covering working with your lender, a loan modification, a pre-foreclosure sale, and a short sale step by step. If the mortgage weighs more than the home can carry, the short sale guidance for West Mount Airy walks through selling for less than you owe with the lender's approval. If your home already went through a listing that did not sell, the expired listing help for West Mount Airy page shows how a relaunch gets it sold. The complete timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia.

If you are weighing bankruptcy against selling in West Mount Airy, you do not have to carry that decision alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language read on your options before the sheriff sale. Every conversation is confidential, and there is no judgment, only solutions.
Your West Mount Airy home
is worth protecting.

Let's talk about your options, on your timeline.

Want to know what your home is worth? Get a real valuation of your home's value.

Licensed. Local. Legit.

Pennsylvania License RS349905 · New Jersey License 1969348
HomeSmart Realty Advisors

Experience. Strategy. Results.

267-977-0304

Need more room to move? Read the full foreclosure and short sale guidance for Philadelphia, see expired listing help in West Mount Airy if your home has already been through a listing that didn't sell, or contact Andre directly.