Can a Divorce Stop a Foreclosure on My Cedarbrook Home in Philadelphia?
No. A divorce does not stop a mortgage foreclosure in Philadelphia. The lender is not a party to your divorce, so a divorce decree that assigns the home to one spouse does not change the mortgage, and the foreclosure case can move forward to a sheriff sale if the payments stay unpaid.
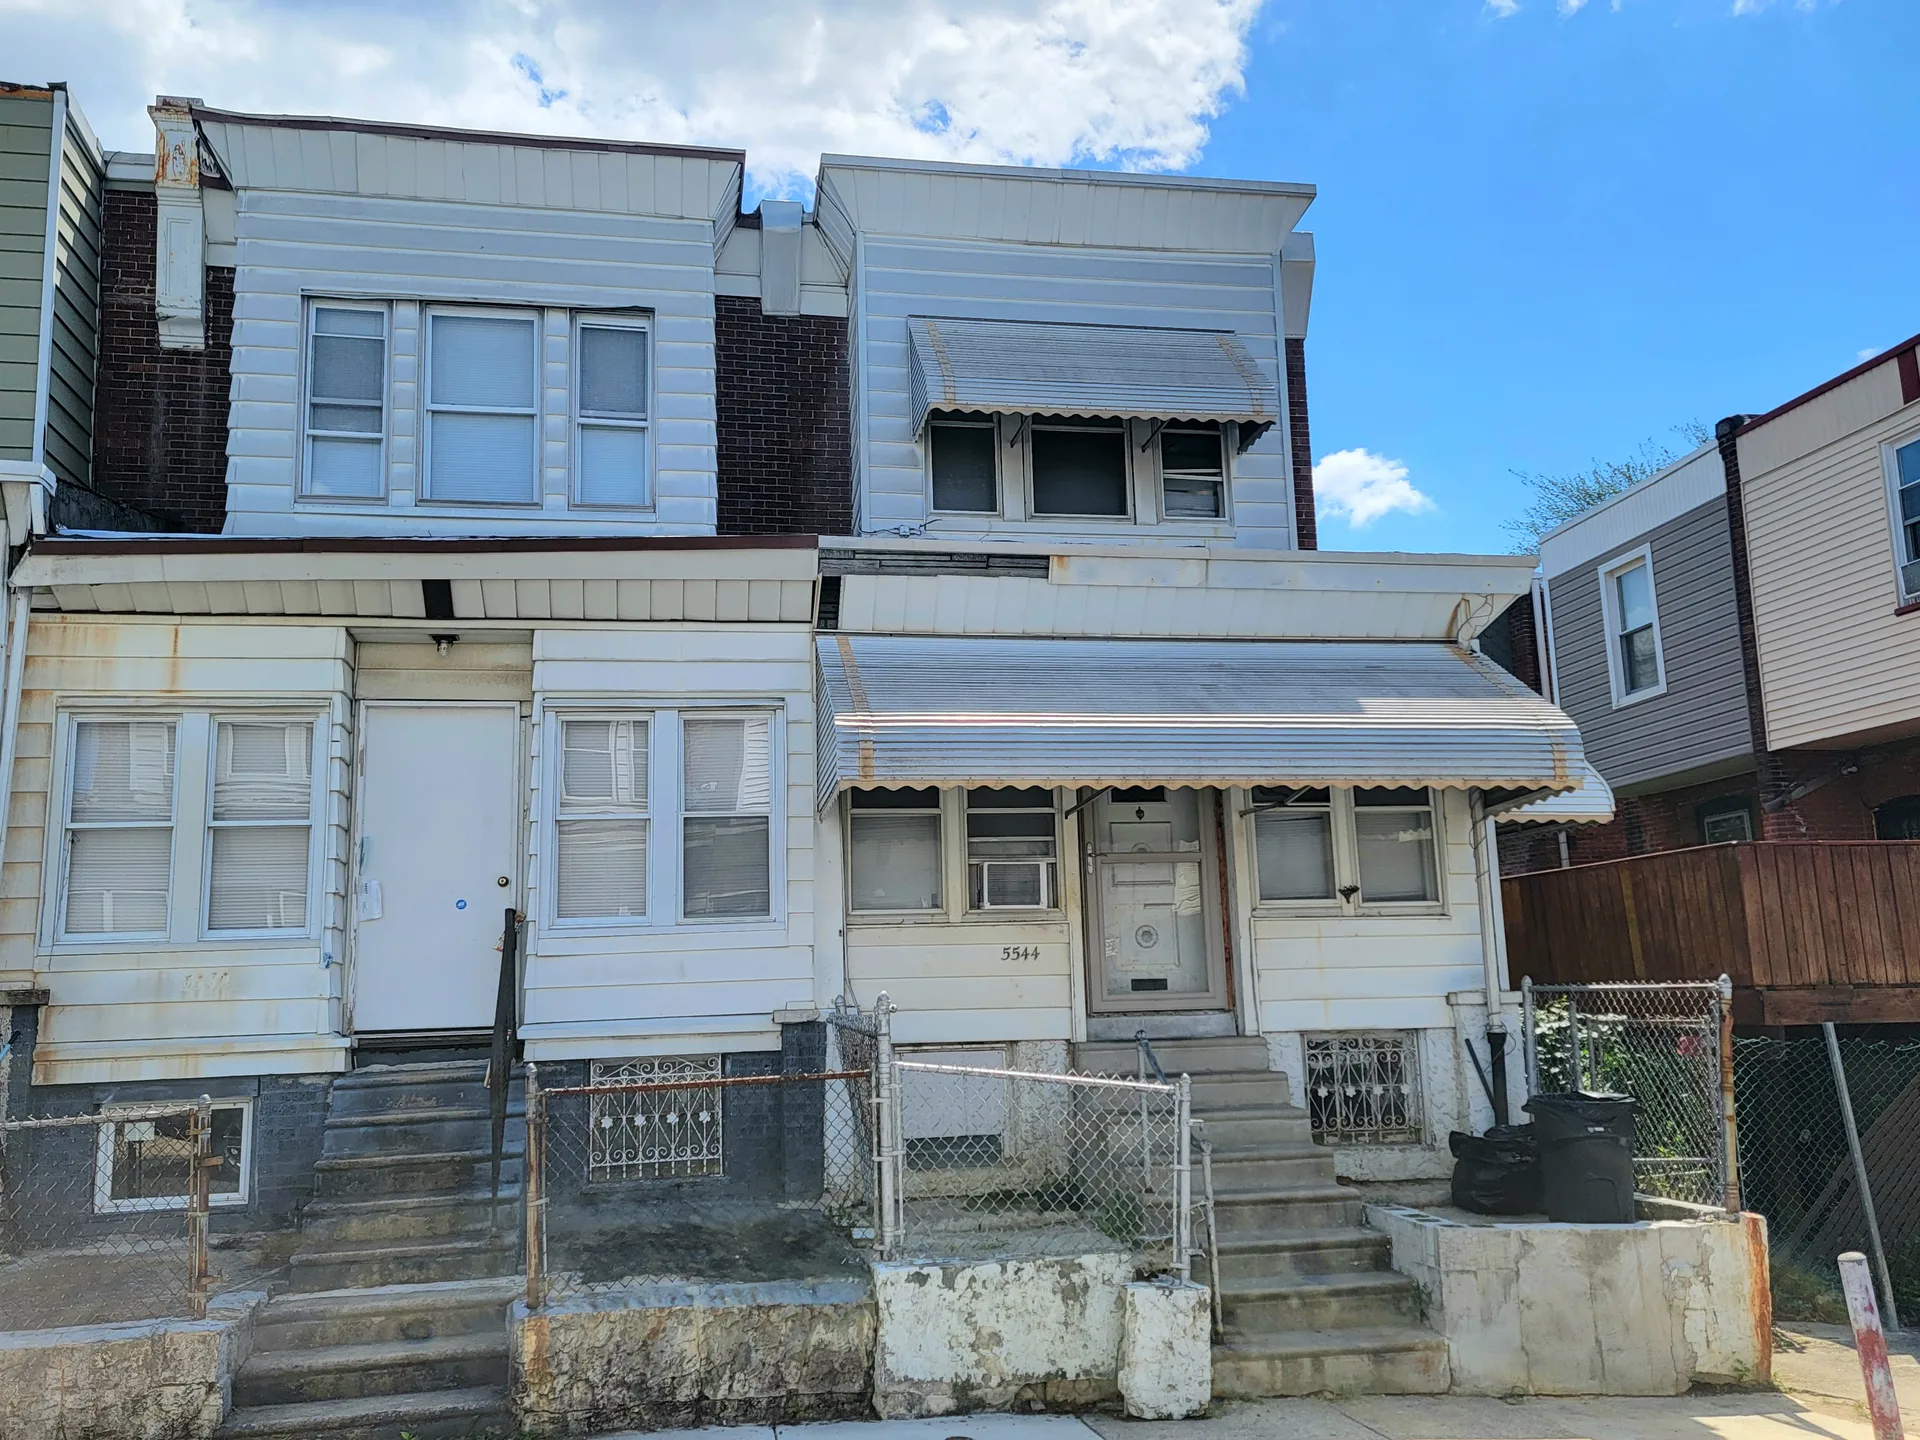
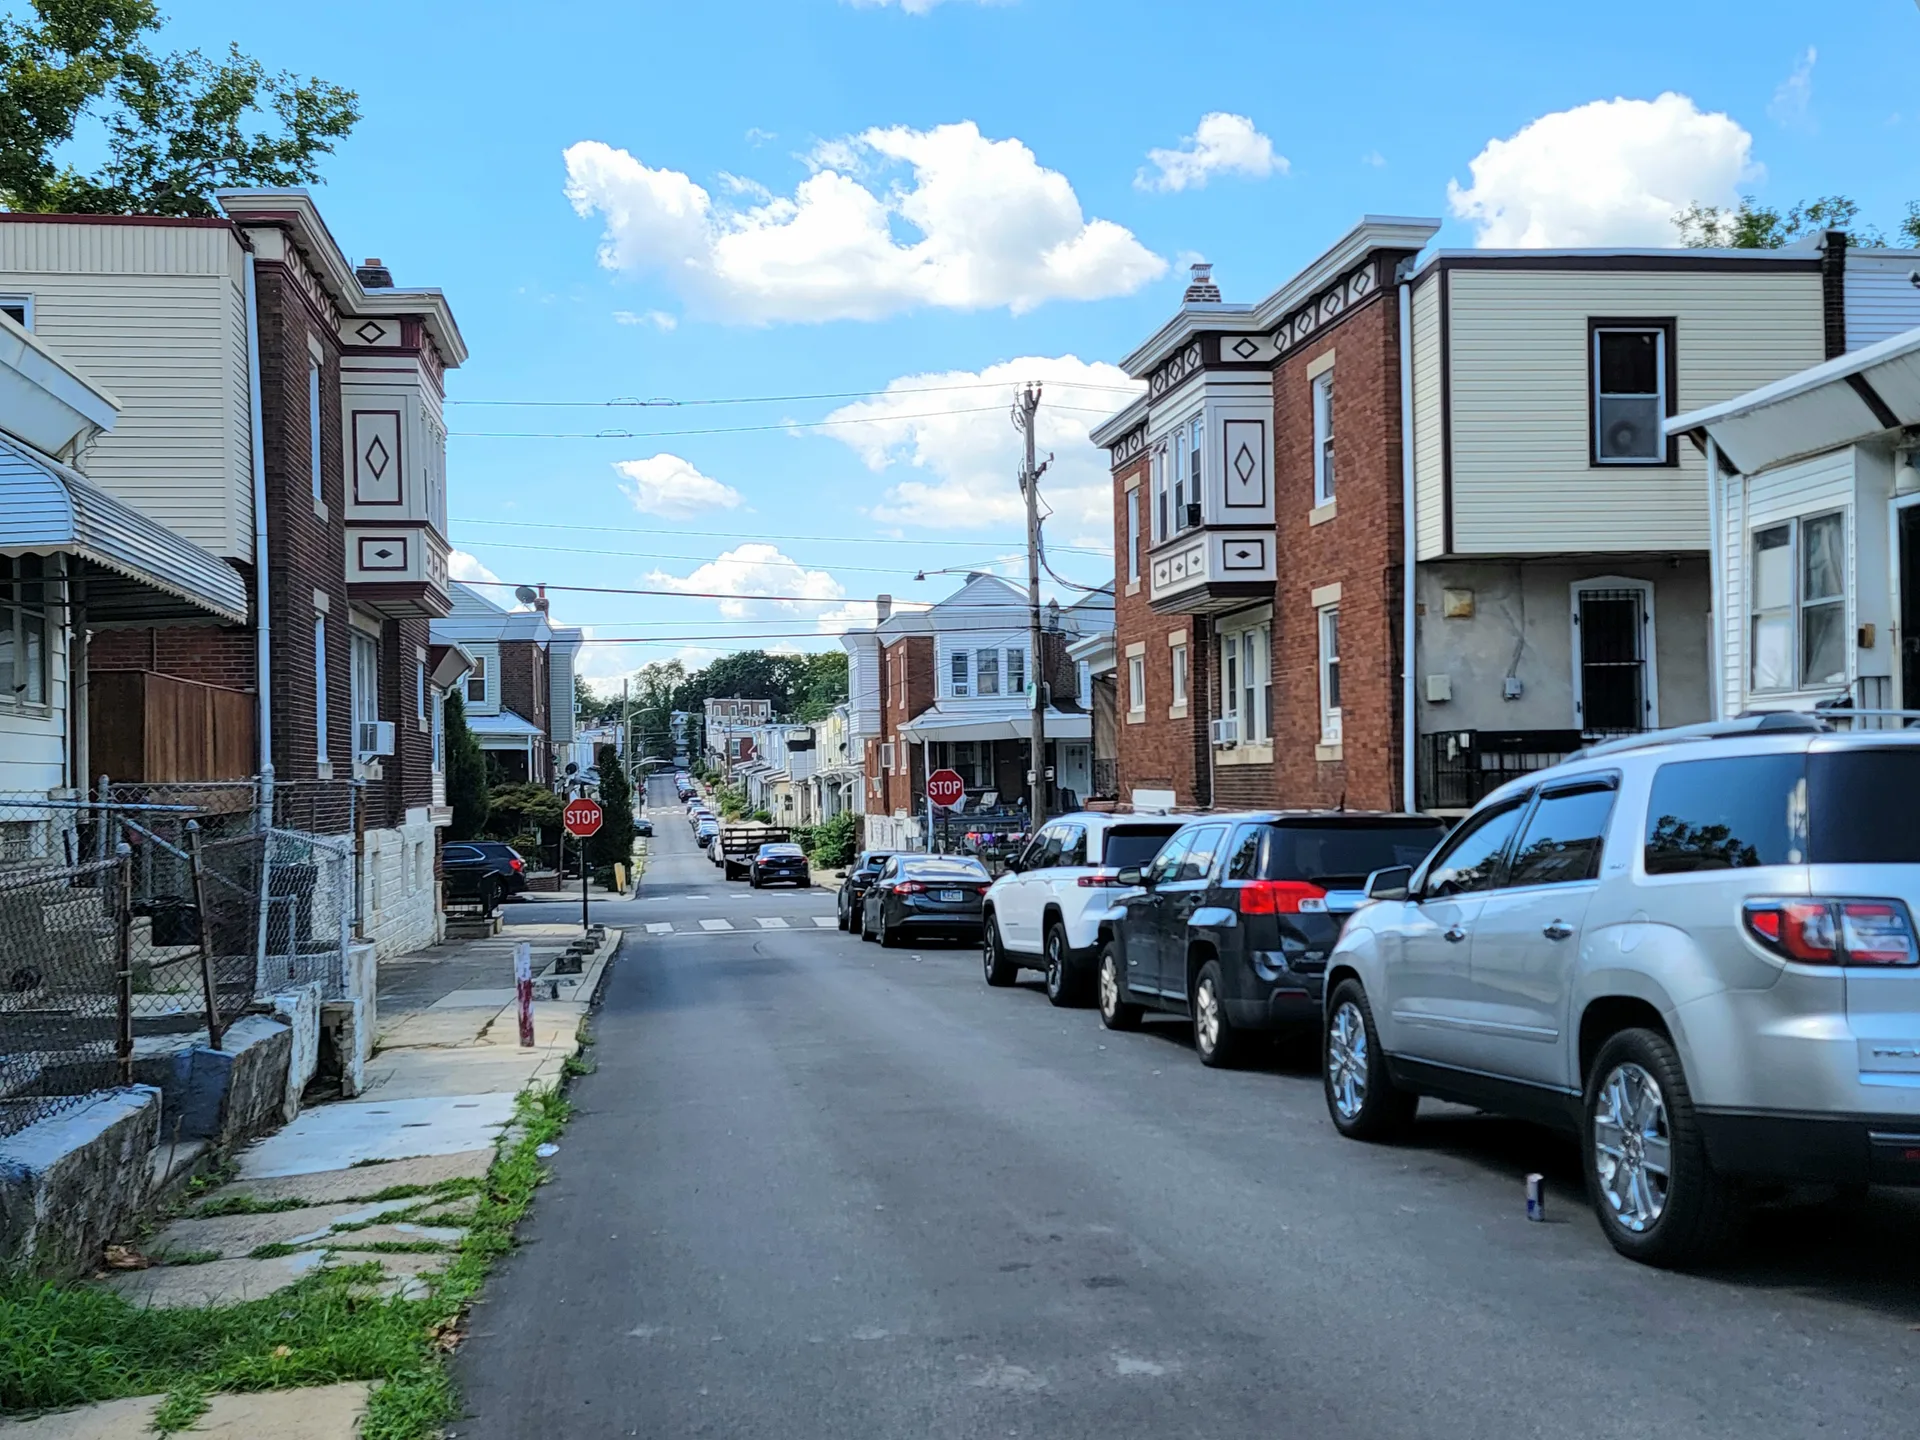
If you live in Cedarbrook, the Northwest Philadelphia neighborhood bordered by Cheltenham Avenue, Stenton Avenue, and Washington Lane, and you are going through a divorce while a sheriff sale date for your home is on the calendar, you may be wondering whether the divorce changes the foreclosure. It does not, and understanding why matters because the choices that protect you are made in the mortgage, not in the divorce papers.
Does the divorce decree protect me from the lender?
No. A divorce decree divides the home and the debts between spouses, but the lender was not part of the divorce and is not bound by it. As long as the mortgage and the promissory note are in force, the lender's right to foreclose stands, and if the payments stop, the case can continue through the Philadelphia courts to a sheriff sale. Both spouses who signed the loan remain on it, and both credit reports are affected if the mortgage goes unpaid.
Can I keep my Cedarbrook home by refinancing in one name?
Yes, if you qualify. Refinancing the mortgage into the name of the spouse who keeps the home is the cleanest way to remove the other spouse from the loan, and a lender-approved mortgage assumption is another route. These are the only ways to actually take a spouse off the mortgage. A divorce decree alone does not do it, no matter what it says about who pays.
What if we sell the home instead?
Selling the home and paying off the mortgage ends the foreclosure threat and turns the home's value into cash the divorce can divide. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender.
What happens if neither of us can pay the mortgage?
If the payments stay unpaid, the foreclosure continues toward a Philadelphia sheriff sale. You still have time before the sale to act: a loan modification can change the terms, a negotiated arrangement can restructure the payments, and a sale on the open market can pay the loan in full. The plan you make before the sale date is the one that protects you.
What should a Cedarbrook homeowner do first?
Talk to your divorce attorney about what the decree can and cannot do, and to a real estate professional about what your home is worth and what a sale could preserve. The two conversations belong together, because the mortgage and the home are handled separately from the divorce. Andre Richardson has 26 years of experience in Philadelphia real estate, and he helps Cedarbrook homeowners sort through these exact choices. The full plan for keeping your options open is laid out on the stop foreclosure help page for Cedarbrook. If the mortgage weighs more than the home can carry, a short sale in Cedarbrook with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If speaking with the lender is the best route, he guides you to coordinate with your lender. If your home has already been through a listing that did not sell, the expired listing help in Cedarbrook page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the legal protections for Philadelphia homeowners facing foreclosure post walks through the rights that apply at each stage.
If a divorce and a sheriff sale date are both on your calendar in Cedarbrook, you do not have to sort through it alone. Call Andre Richardson at 267-977-0304 or book a free consult, and get a plain-language plan for refinancing, negotiating, or selling before the sale. Every conversation is confidential, and there is no judgment, only solutions.