Can the Bank Garnish My Wages After Foreclosure on My Somerton Home in Philadelphia?
No. In Pennsylvania, a lender generally cannot garnish your wages over a foreclosure deficiency, because state law bars wage garnishment for most consumer debts. The real risk is a deficiency judgment, which the lender can enforce against money in your bank account, so the move that protects you is addressing the shortfall before it becomes a judgment.
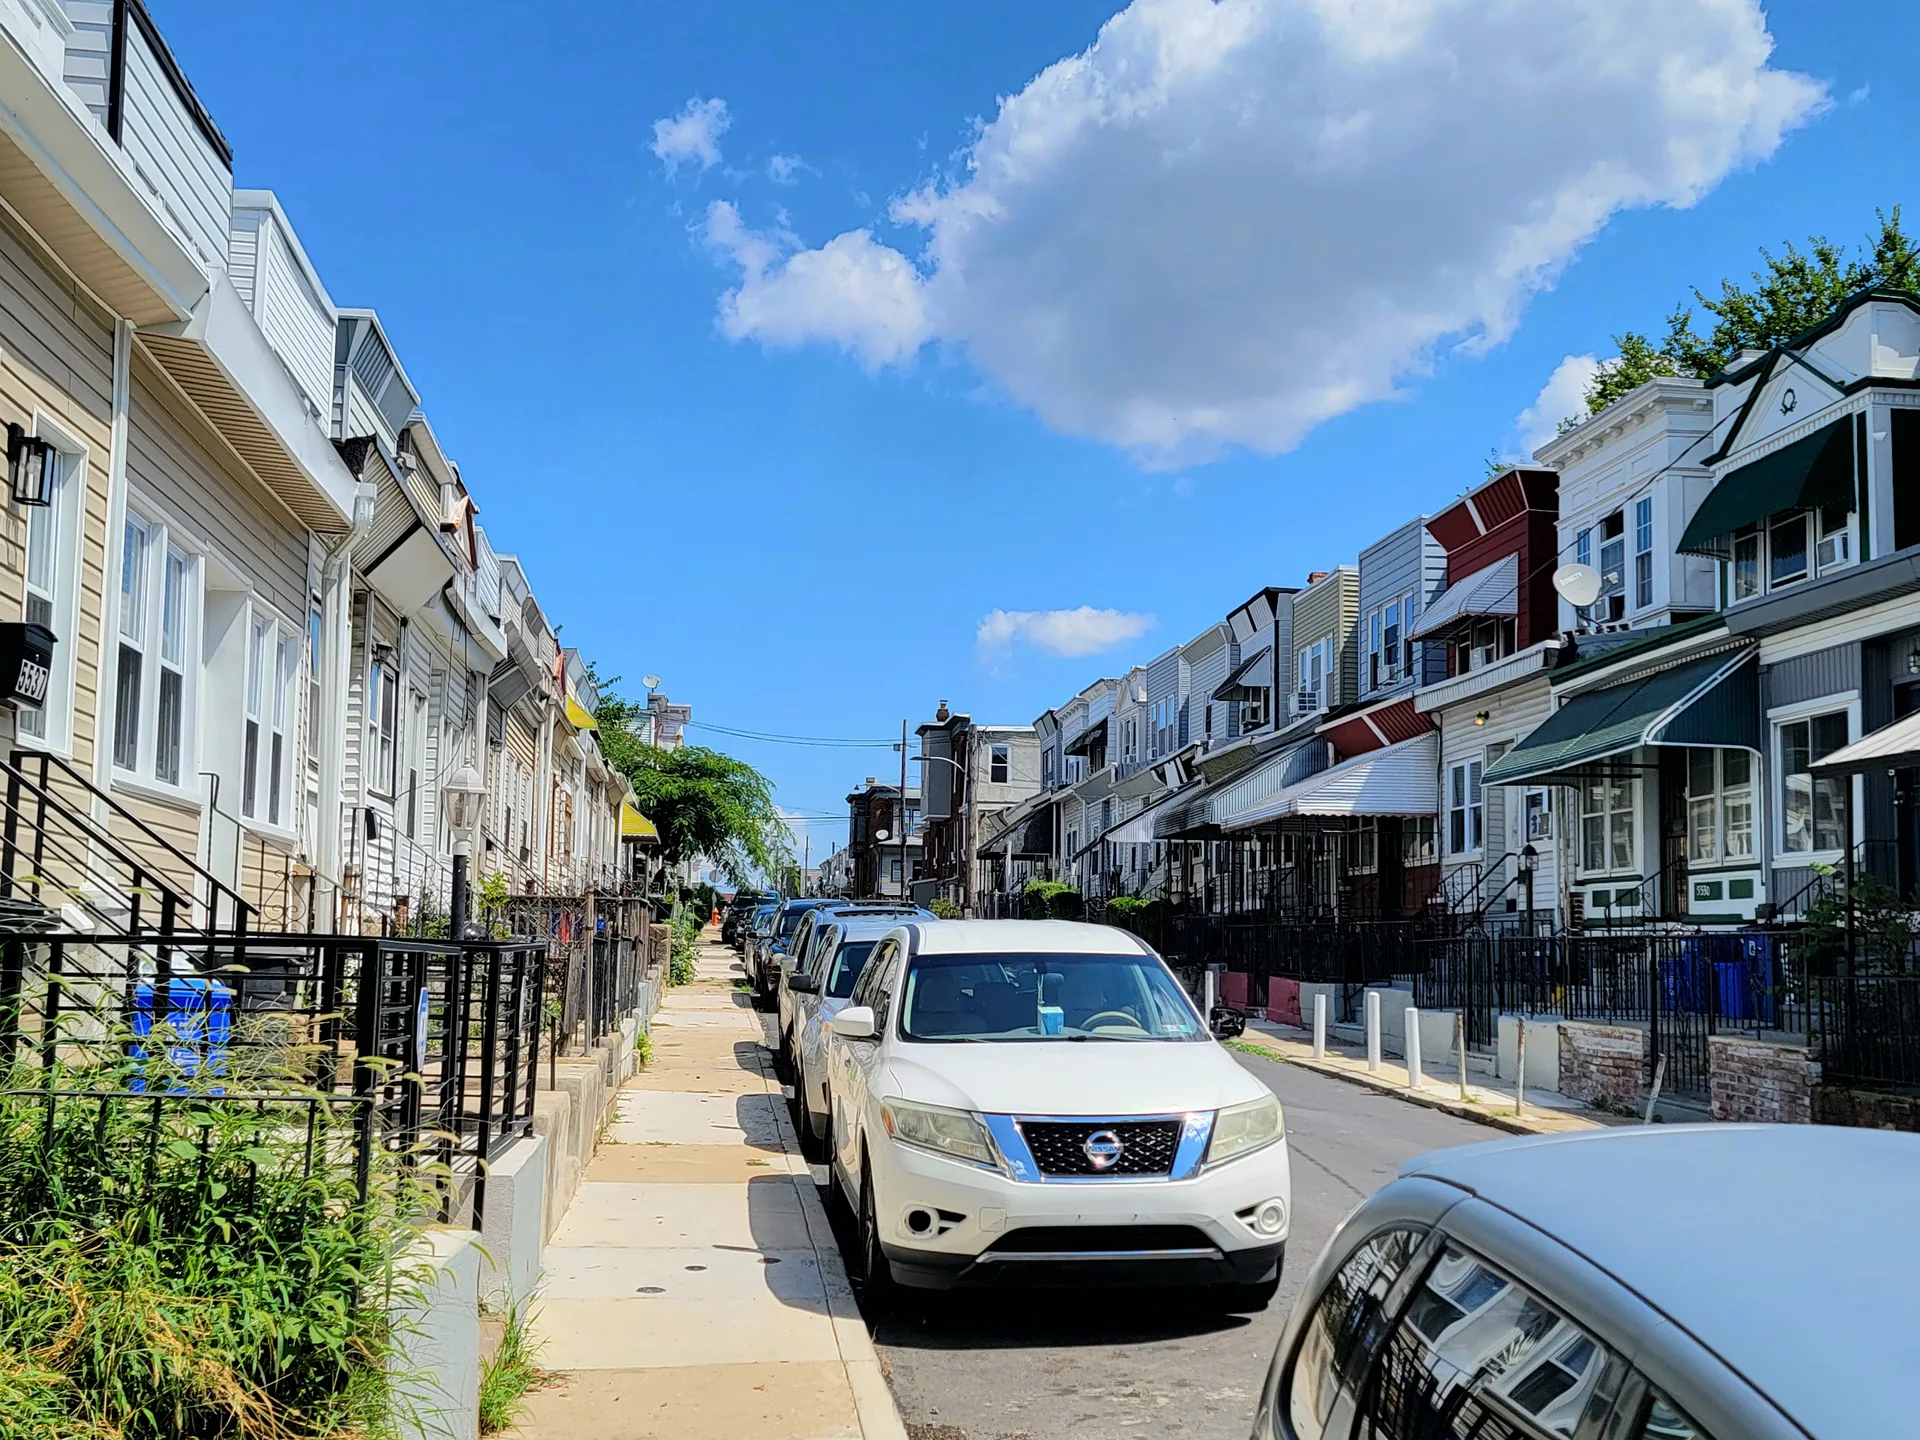
If you live in Somerton, the far Northeast corner of Philadelphia along the Montgomery County border, your home is likely a 1960s brick townhome or duplex with a garage and a wider lot. When a sheriff sale ends, the worry does not always end with it. Homeowners across Somerton ask the same question: after the home is gone, can the lender still reach into my paycheck? It is a fair question, and the answer in Pennsylvania is more protective than many people expect, with one important catch.
Can a Lender Garnish My Wages in Pennsylvania After Foreclosure?
Generally, no. Pennsylvania law bars wage garnishment for most consumer debts, and a mortgage deficiency falls into that category. The narrow exceptions are obligations like child support, student loans, and taxes. So the fear of a lender taking a cut of every paycheck after a Somerton foreclosure is, for most homeowners, not what happens. What the lender can do instead is pursue a deficiency judgment, and that changes the picture.
What Is a Deficiency Judgment and When Can the Lender File One?
Pennsylvania is a recourse state. If your Somerton home sells at the sheriff sale for less than the balance you owe, the lender can ask the court for a deficiency judgment covering the difference. There is a deadline: the lender must file the deficiency action within six months of the sheriff's deed being transferred after the sale. Miss that window, and the lender generally loses the right to collect the shortfall. That deadline is real, and knowing it is the first step to knowing whether the threat applies to you.
Can the Lender Take Money From My Bank Account?
Yes, and this is the part Somerton homeowners should take seriously. Once a lender holds a deficiency judgment, it is enforced like any other civil judgment, which can include garnishing funds in your bank account, and Pennsylvania judgments can be collected for up to 20 years. That is why a deficiency judgment is worth avoiding entirely rather than hoping it quietly goes away.
How Can a Somerton Homeowner Avoid a Deficiency Judgment?
The cleanest way is to sell before the sheriff sale, so the home is sold by you rather than auctioned by the court. Somerton's townhomes and duplexes, with their garages and wider lots, hold steady appeal to buyers who want a suburban feel without leaving the city, including first-time buyers, downsizers, and commuters who value the easy access to Montgomery County and I-95. If the mortgage weighs more than the home can carry, a short sale with the lender's approval can end the process, and the short sale agreement should include a deficiency waiver, a written provision that the lender will not come after you for the difference. Andre works to try and secure a deficiency waiver in every short sale he guides. If speaking with the lender is the best route, he guides you to coordinate with your lender.
What Should a Somerton Homeowner Do First?
Start by getting a clear picture of what your Somerton home is worth today and how far the arrears have grown. The full plan for keeping your options open is laid out on the stop foreclosure help page for Somerton. If selling before the sale date makes sense, a short sale in Somerton with the lender's approval can end the threat of foreclosure, and Andre works to try and secure a deficiency waiver so the lender does not come after you for the difference. If your home has already been through a listing that did not sell, the expired listing help for Somerton page shows how a relaunch gets it sold. The full timeline, credit impacts, and lender negotiations are covered in the foreclosure and short sale guidance for Philadelphia, and the sell my house process explains a pre-foreclosure sale start to finish.
If the sheriff sale is behind you or the papers have just arrived, you do not have to face the money questions alone. Call Andre at 267-977-0304 or book a free consult for a straight answer about your balance, your equity, and whether a deficiency judgment is even a risk. You can also reach Andre through the contact page. Every conversation is confidential, and there is no judgment, only solutions.